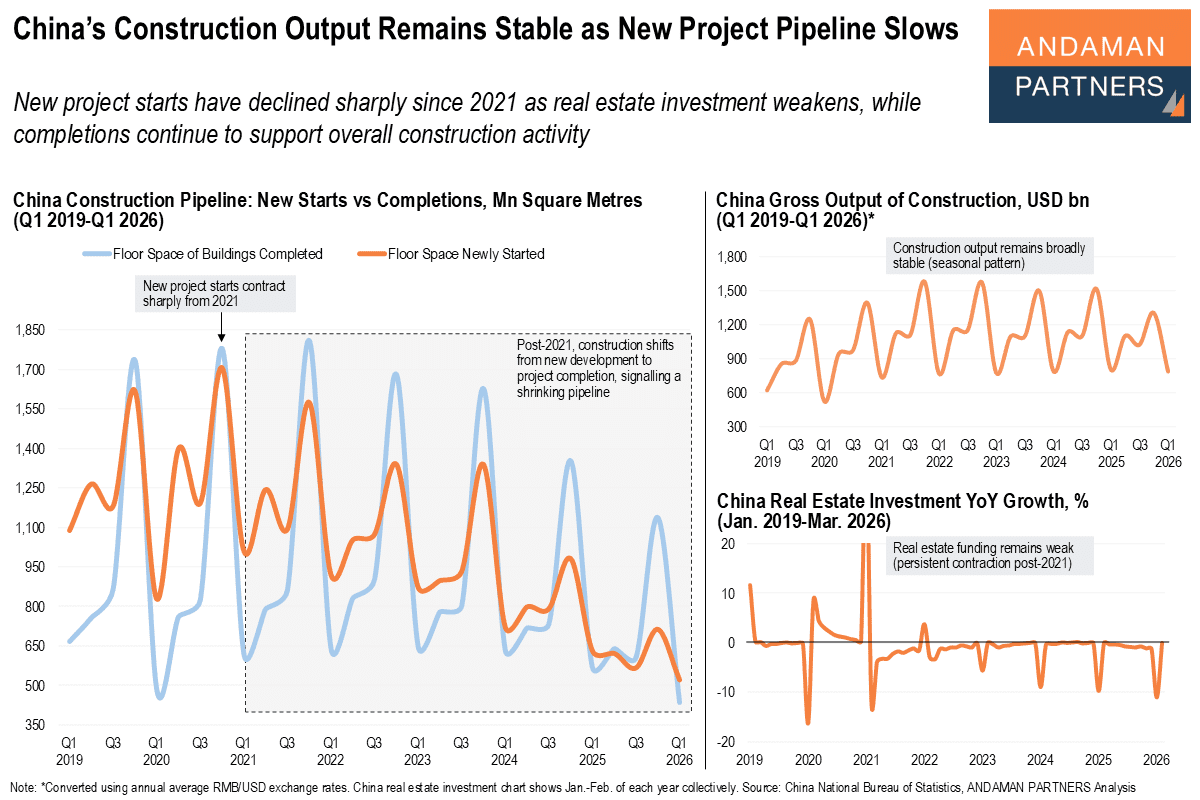
China’s Construction Output Remains Stable as New Project Pipeline Slows
New project starts have declined sharply since 2021 as real estate investment weakens, while completions continue to support overall construction activity.
New project starts have declined sharply since 2021 as real estate investment weakens, while completions continue to support overall construction activity.
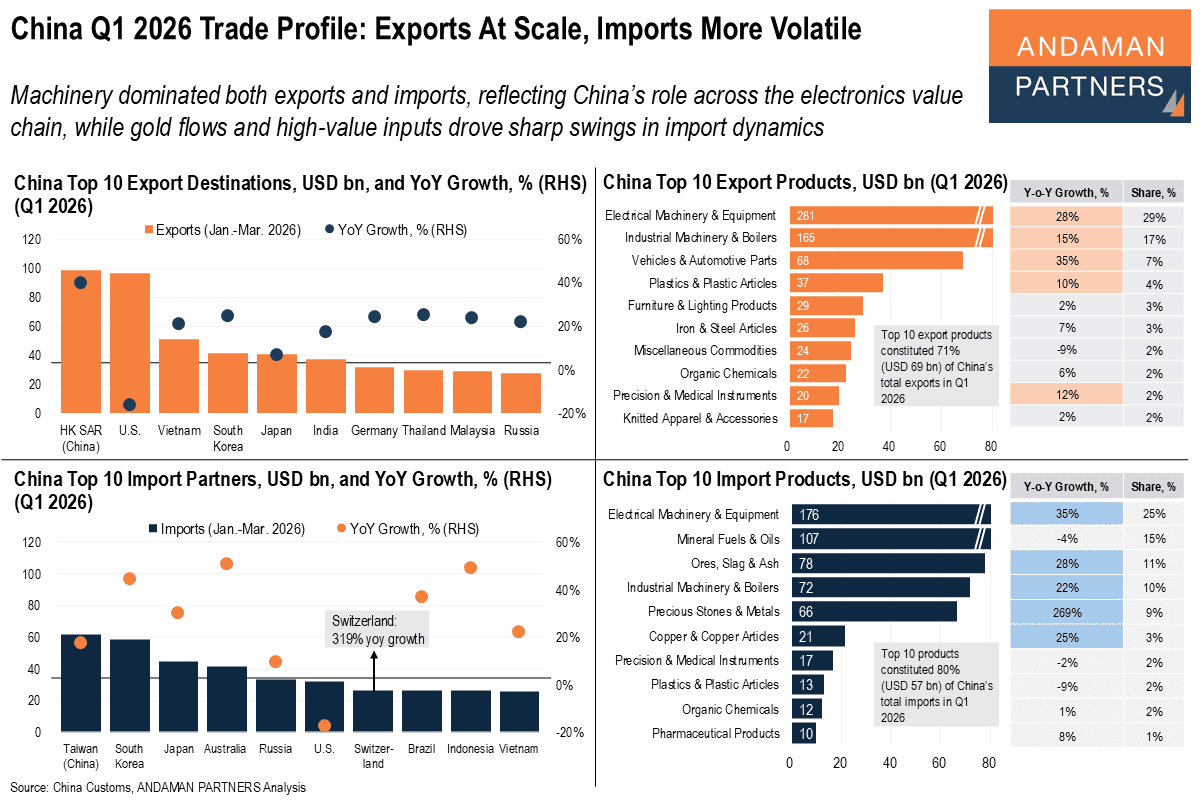
Machinery dominated exports and imports, reflecting China’s role across the electronics value chain; gold and high-value inputs drove import swings.
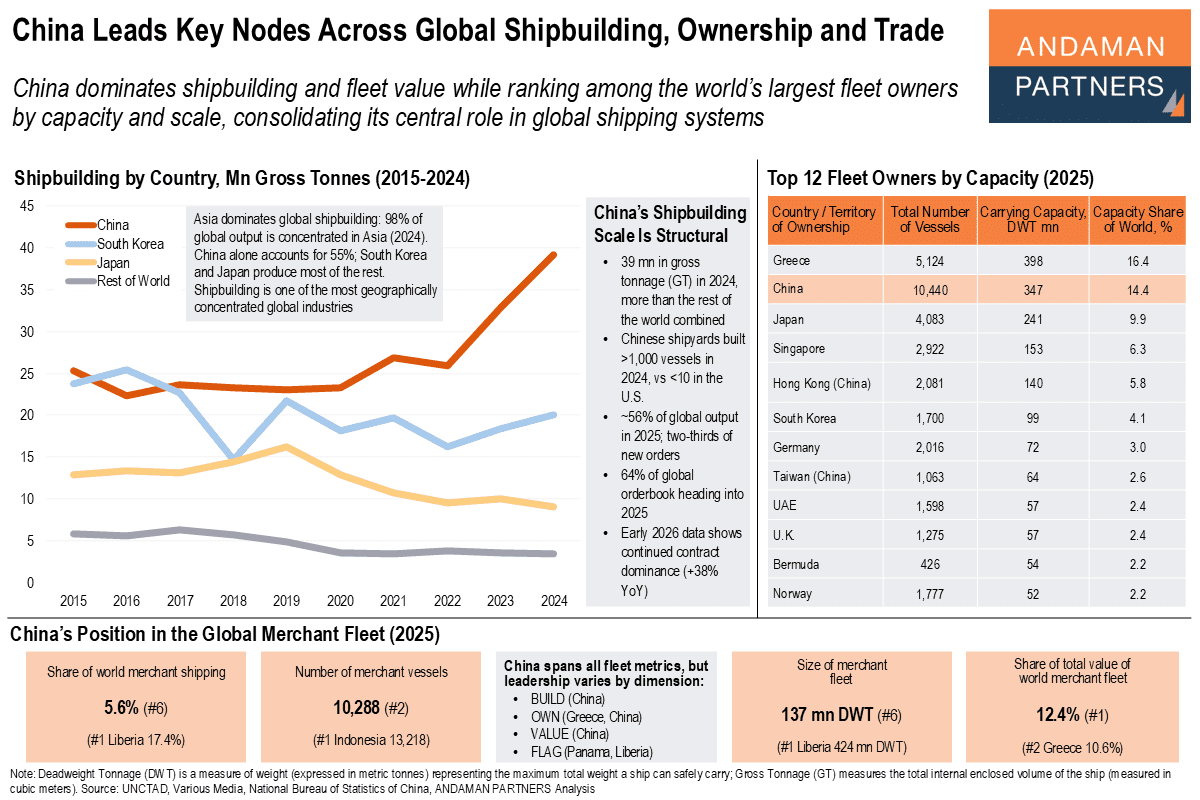
China dominates shipbuilding and fleet value while ranking among the world’s largest fleet owners by capacity and scale.
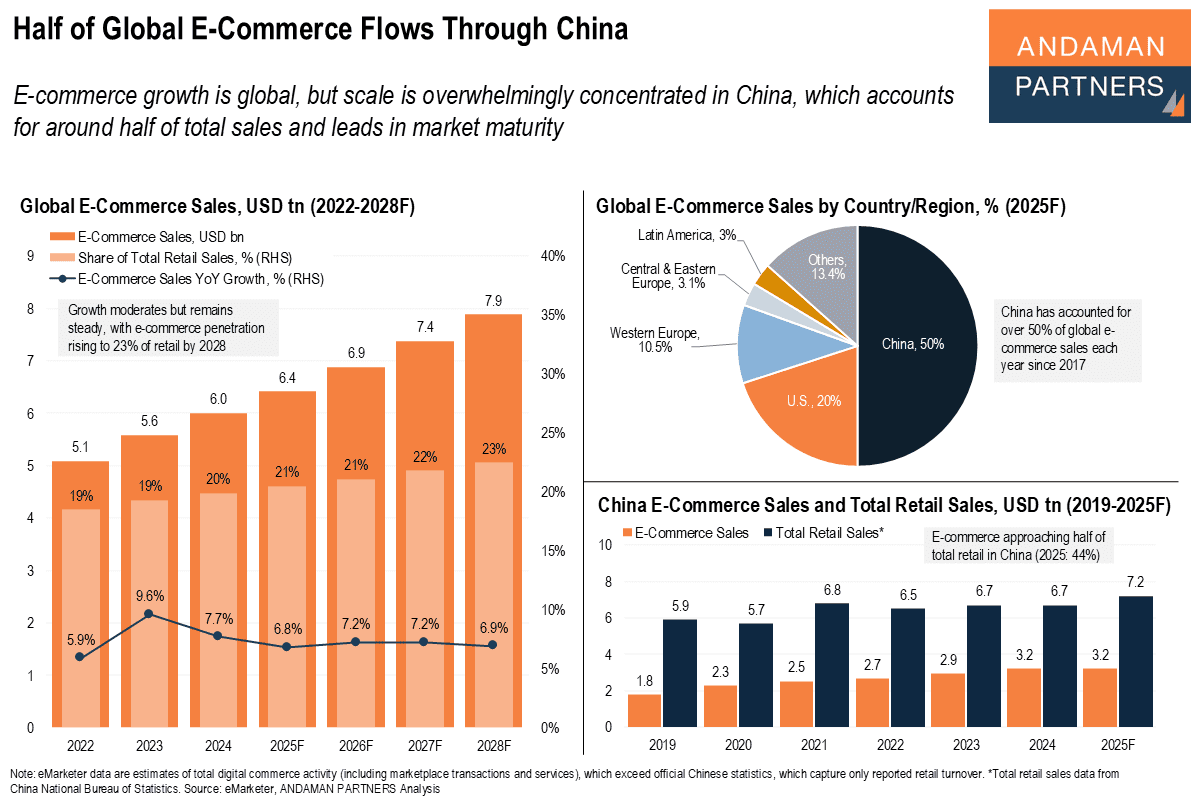
E-commerce growth is global, but scale is overwhelmingly concentrated in China.
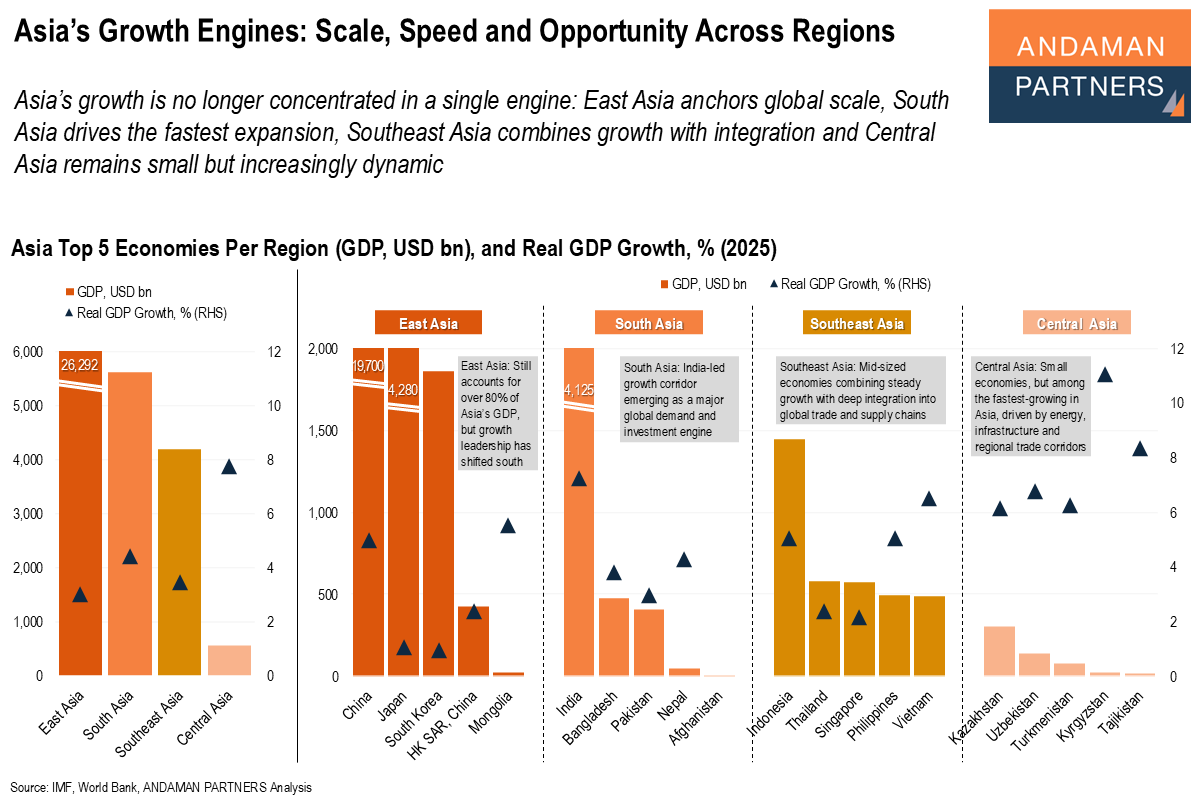
Asia's scale, speed and integration are no longer concentrated in a single core, but spread across multiple, complementary engines.
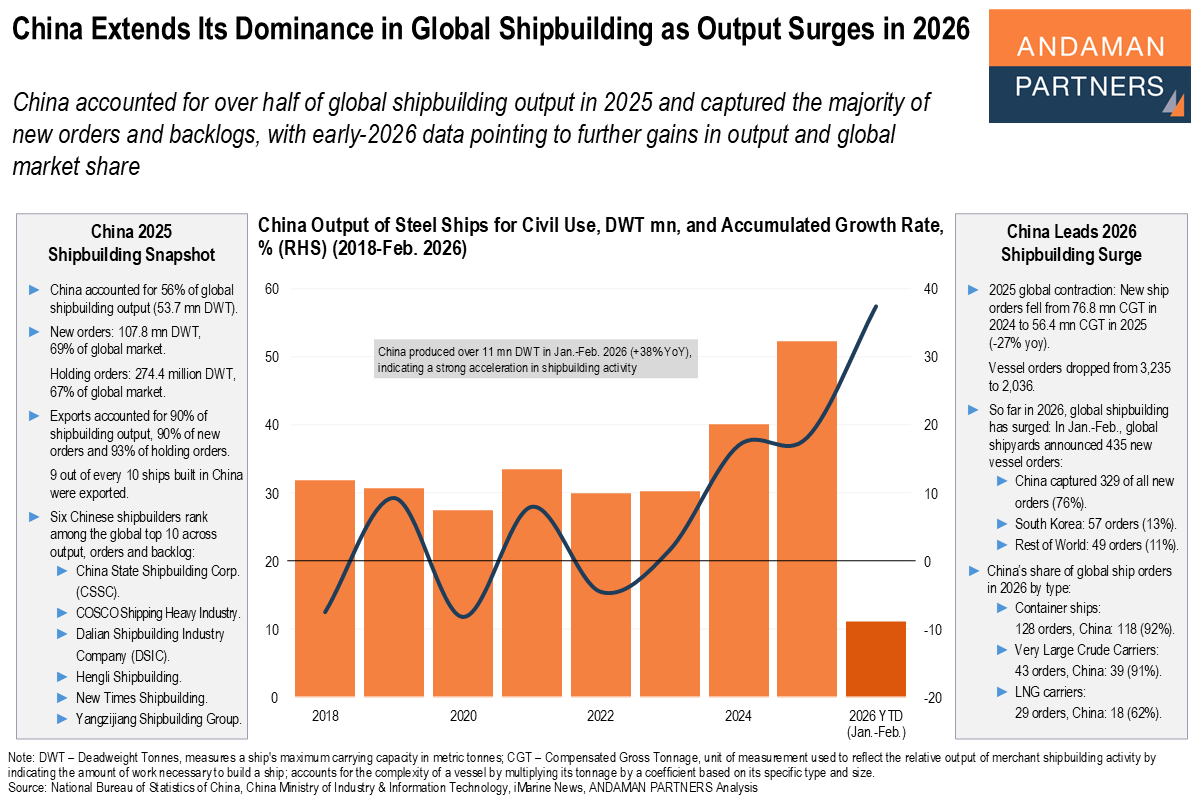
Even as global ship orders declined in 2025, early-2026 data shows a rapid rebound, with China securing the vast majority of new contracts.
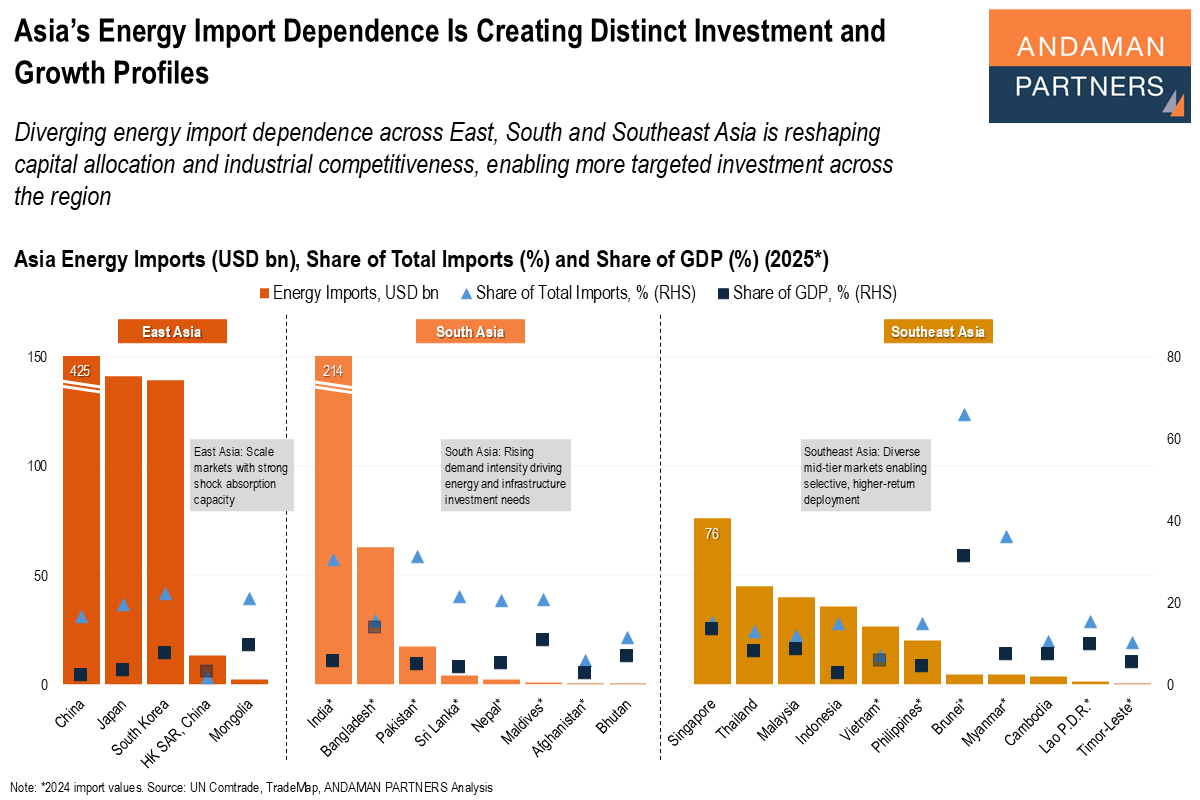
Diverging energy import dependence across Asia is enabling more targeted investment across the region.
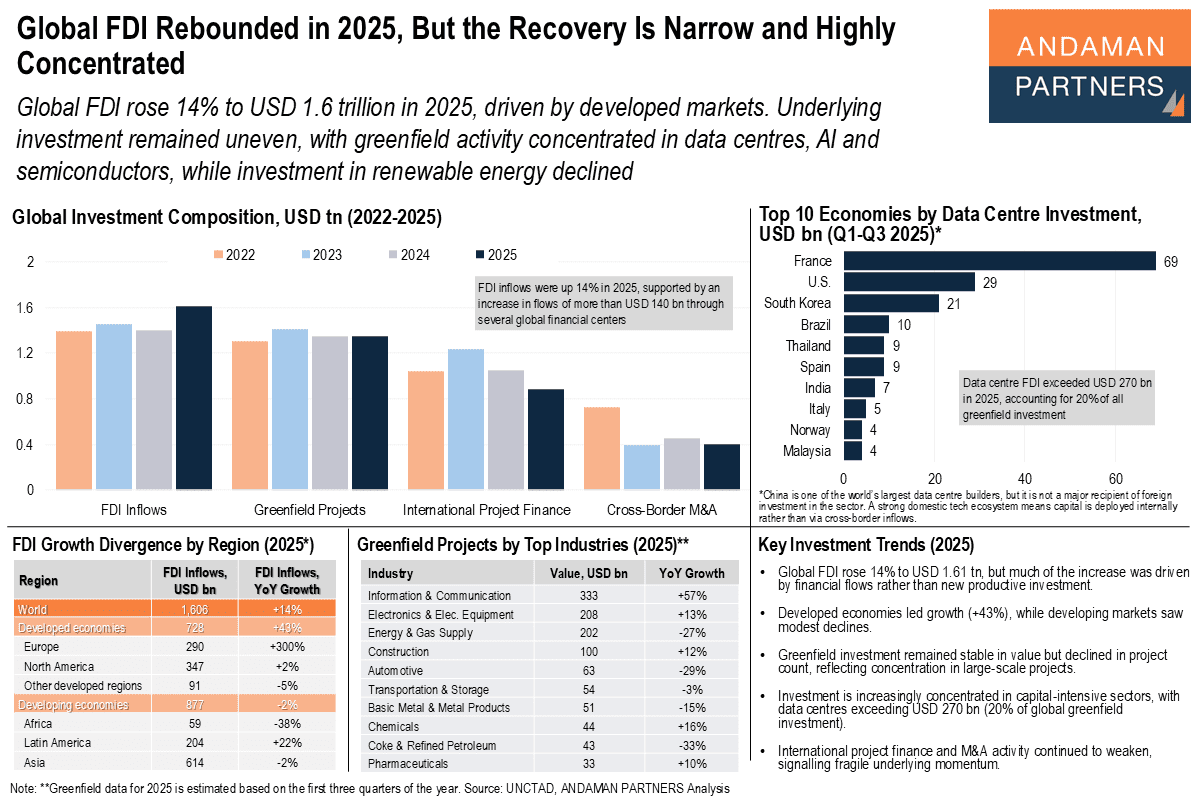
Investment remained uneven, with greenfield activity concentrated in data centres, AI and semiconductors.
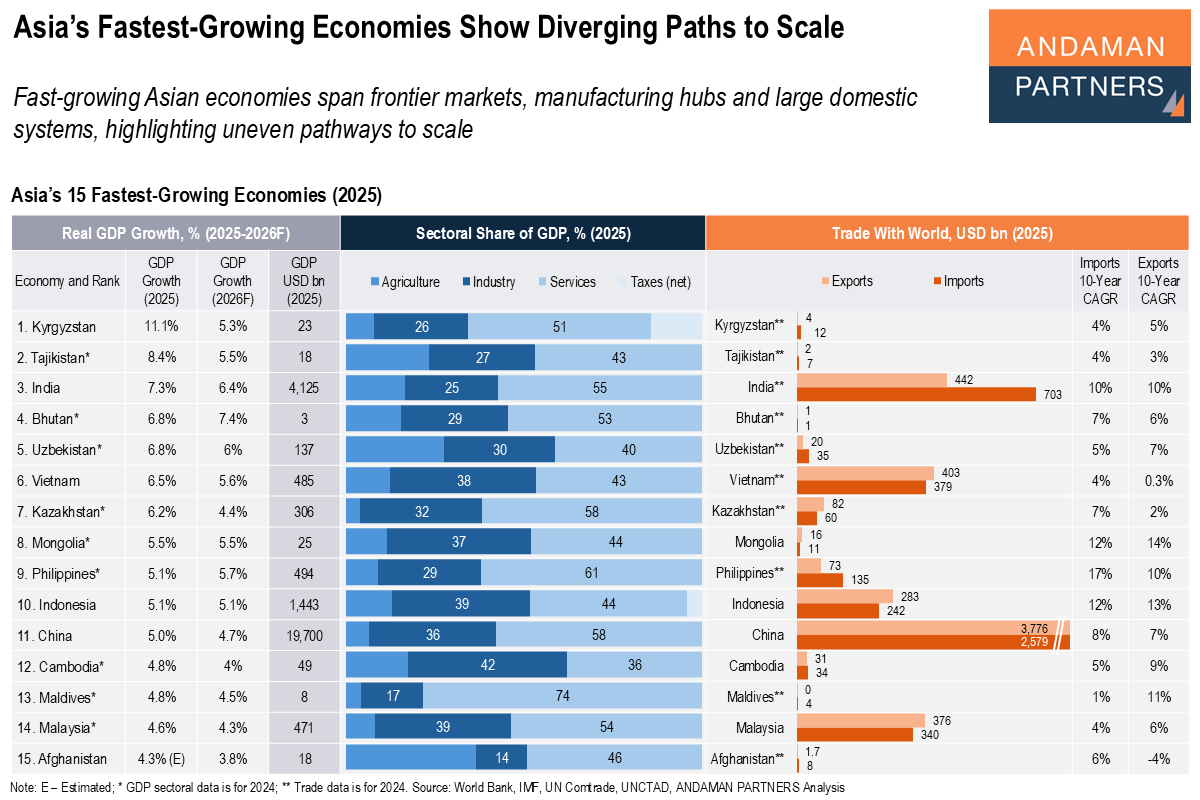
Fast-growing Asian economies span frontier markets, manufacturing hubs and large domestic systems, highlighting uneven pathways to scale.
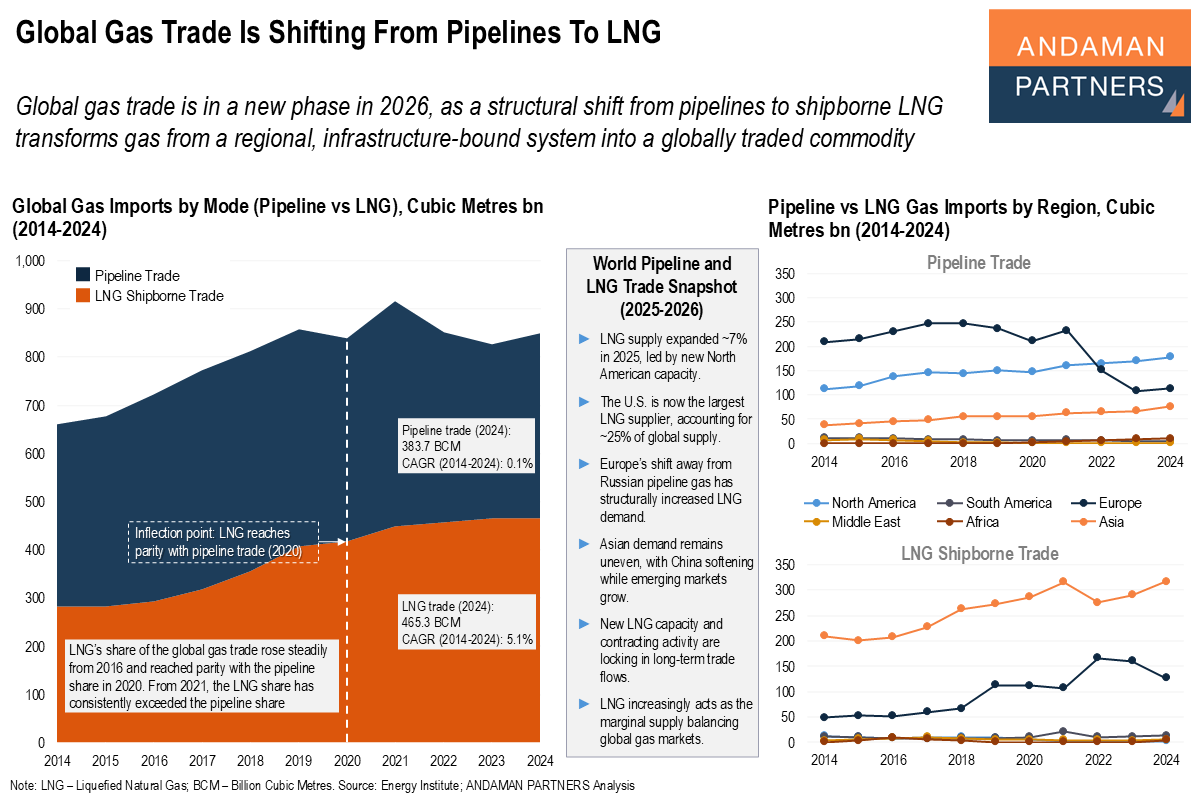
Global gas trade is in a new phase in 2026 amid a structural shift from pipelines to shipborne LNG.