Machinery dominated both exports and imports, reflecting China’s role across the electronics value chain, while gold flows and high-value inputs drove sharp swings in import dynamics.
China’s trade in Q1 2026 showed a stabilising but uneven recovery, defined by strong electronics flows, concentrated product structures and volatile import dynamics.
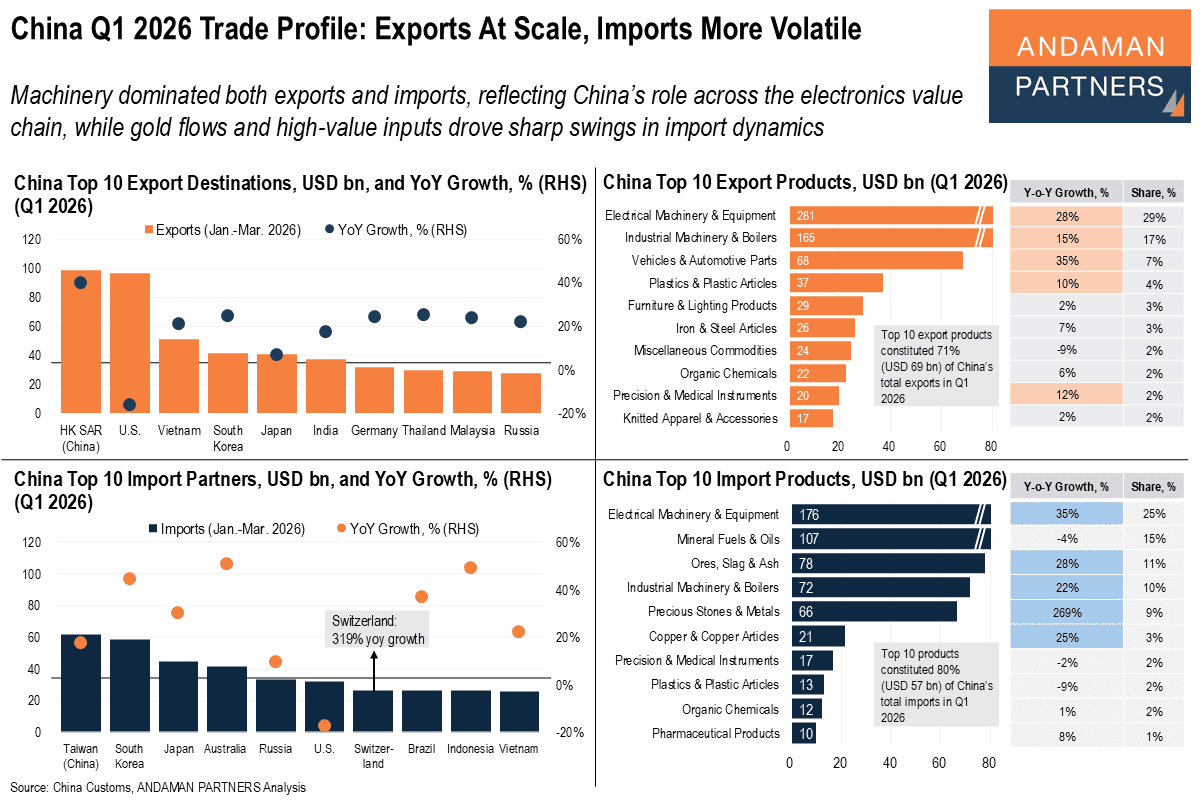
Exports remained anchored in a handful of major markets: Hong Kong (USD 100 billion) and the U.S. (USD 97 billion) led by wide margins, followed by Vietnam (USD 52 billion) and South Korea (USD 43 billion). Growth was broadly positive across partners, with export yoy expansion typically in the 20-30% range, signalling steady external demand despite a more moderate overall trade environment.
The U.S. still ranks among China’s largest trade partners but has shown continued softness, with around -20% growth in both China’s exports and imports in Q1.
On the product side, exports are highly concentrated. Electrical machinery and equipment alone reached USD 281 billion, accounting for 29% of total exports, followed by industrial machinery (USD 165 billion, 17%) and vehicles (USD 68 billion, 7%). The top ten export products accounted for 71% of total exports, underscoring the centrality of industrial and technology goods.
Imports followed a more volatile pattern. China’s largest import partners: Taiwan, China (USD 62 billion), South Korea (USD 59 billion) and Japan (USD 44 billion) reflect China’s dependence on regional supply chains. However, Switzerland (USD 27 billion) stands out with a 319% yoy surge, driven primarily by gold (over 70% of imports) and high-value pharmaceuticals, with base effects and shipment patterns amplifying growth.
By product, imports are equally concentrated: electrical machinery led at USD 176 billion (25%), followed by mineral fuels (USD 107 billion) and ores (USD 78 billion). Electrical machinery dominated both imports and exports because it spans the full electronics value chain. China imports high-end components such as semiconductors while exporting finished goods like smartphones and telecom equipment.
Overall, Q1 2026 reflects a trade system that is large, concentrated and structurally anchored in electronics, but with increasingly uneven import dynamics.
Also by ANDAMAN PARTNERS:
ANDAMAN PARTNERS supports international business ventures and growth. We help launch global initiatives and accelerate successful expansion across borders. If your business, operations or project requires cross-border support, contact connect@andamanpartners.com.

How an Inland City Became One of China’s Top 5 Economies by ANDAMAN PARTNERS Co-Founder Rachel Wu
Analysis by ANDAMAN PARTNERS Co-Founder Rachel Wu on how Chongqing became one of China’s top 5 economies
China’s Role in Global Capex Project Procurement by ANDAMAN PARTNERS Co-Founder Rachel Wu
Analysis by ANDAMAN PARTNERS Co-Founder Rachel Wu on how China’s role has evolved in global capex project procurement
ANDAMAN PARTNERS Co-Founder Rachel Wu to Deliver Talk at SEP Global Reunion 2026 in Shanghai, China
Rachel will deliver a talk at the event entitled ‘Two SEPers in the Family – Building in China for 20+ Years’
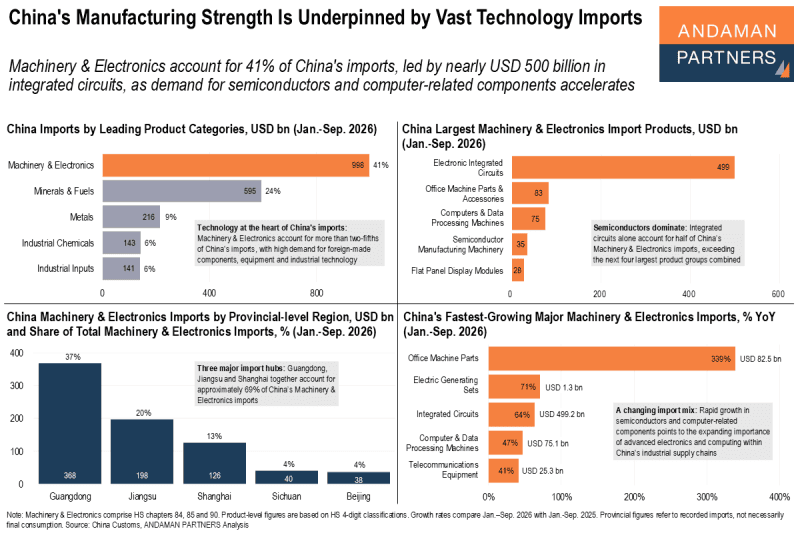
China’s Manufacturing Strength Is Underpinned by Vast Technology Imports
Machinery & Electronics account for 41% of China’s imports, led by nearly USD 500 billion in integrated circuits
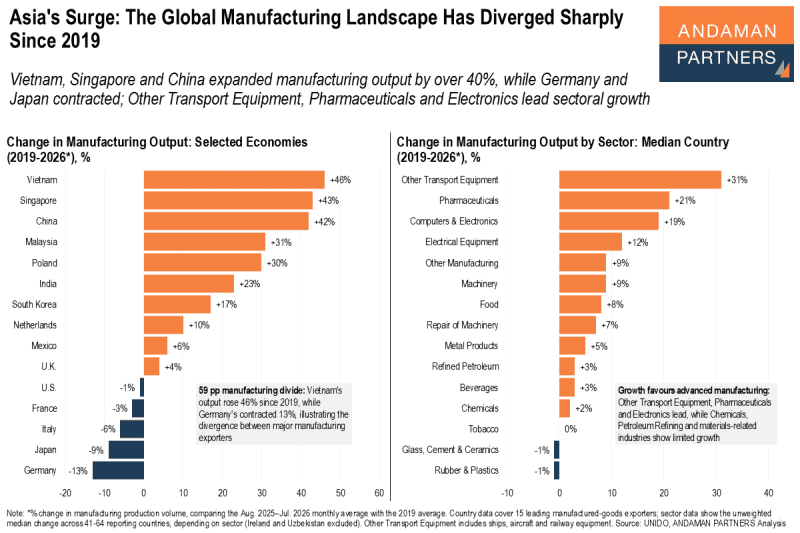
Asia’s Surge: The Global Manufacturing Landscape Has Diverged Sharply Since 2019
Vietnam, Singapore and China expanded manufacturing output by over 40%, while Germany and Japan contracted
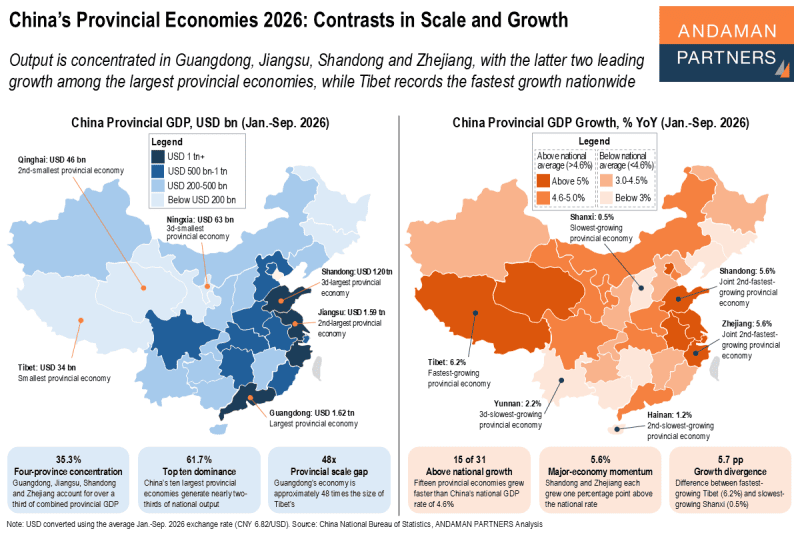
China’s Provincial Economies 2026: Contrasts in Scale and Growth
Output is concentrated in Guangdong, Jiangsu, Shandong and Zhejiang, while Tibet records the fastest growth nationwide