Fixed asset investment (FAI) remains one of the most important indicators for understanding China’s economic trajectory. Unlike consumption or trade, FAI captures the scale and direction of capital formation across infrastructure, manufacturing, real estate and industrial capacity.
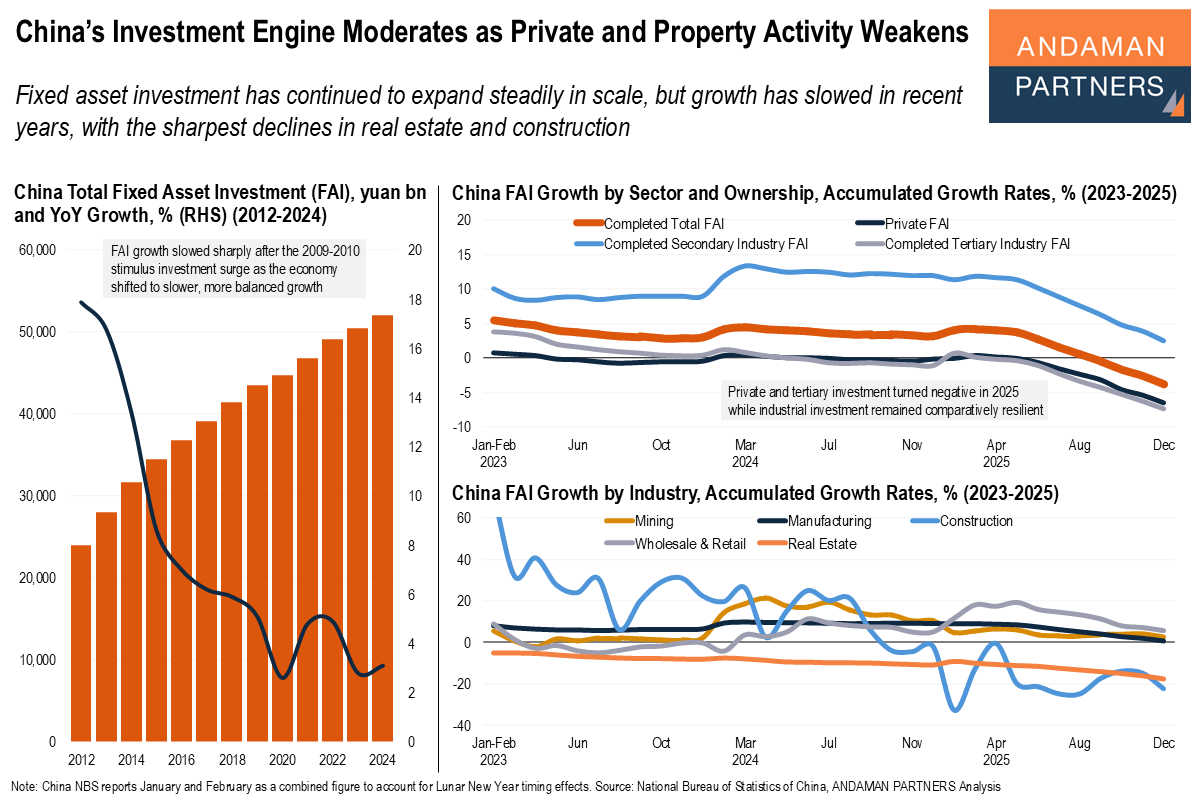
For decades, investment has been a central pillar of China’s growth model, financing the construction of transport networks, energy systems, housing and industrial facilities that underpin the country’s economic expansion. The scale of this investment machine is enormous: annual FAI has continued to rise in absolute terms, reaching more than RMB 50 trillion (around USD 7 trillion) by 2024.
At the same time, the data show a clear moderation in investment growth over the past decade. Following the powerful stimulus-driven surge in 2009-2010, which pushed investment growth to very high levels, the pace of expansion gradually slowed as China’s economy matured and policymakers sought to rebalance growth away from credit-fuelled construction and infrastructure spending. The result has been a steady decline in FAI growth rates from the high teens in the early 2010s to low single digits in recent years, and negative growth in 2025.
More recent data also highlight important shifts within China’s investment structure. Private sector investment has weakened and turned negative in 2025, signalling subdued business confidence and tighter financing conditions. Investment in tertiary sectors, which include services and real estate, has also contracted, reflecting the prolonged downturn in the property market.
In contrast, investment in secondary industries such as manufacturing and mining has remained comparatively resilient. Investment in mining has also been supported by efforts to strengthen the domestic supply of critical minerals and energy resources. Together, these patterns suggest that China’s investment engine is becoming more selective, with industrial upgrading and strategic sectors sustaining capital spending even as property-driven growth continues to fade.
In 2025, the sectoral data underline this divergence. Total FAI growth turned negative by the end of the year, while private investment declined by 6.4% and tertiary sector investment fell by roughly 7.4%. By contrast, investment in secondary industries remained positive, growing at 2.5% year-on-year. Within this category, capital spending has been concentrated in the manufacturing and resource sectors aligned with China’s industrial policy priorities, including advanced manufacturing, electric vehicles and batteries, semiconductors, industrial machinery, and renewable energy supply chains.
These trends suggest that while China’s overall investment cycle is slowing, capital formation continues to be directed toward strategic industrial upgrading and energy transition sectors.