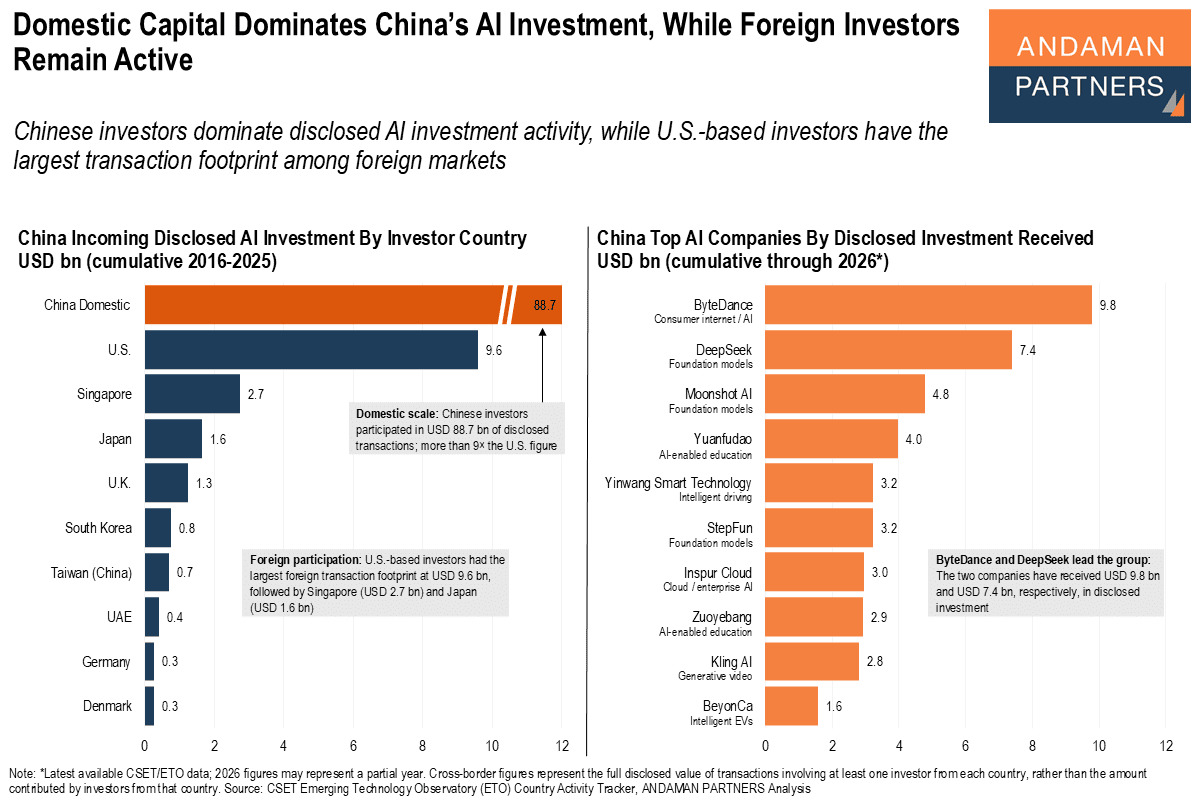
Domestic Capital Dominates China’s AI Investment, While Foreign Investors Remain Active
Chinese investors dominate disclosed AI investment activity, while U.S.-based investors have the largest transaction footprint among foreign markets
Chinese investors dominate disclosed AI investment activity, while U.S.-based investors have the largest transaction footprint among foreign markets
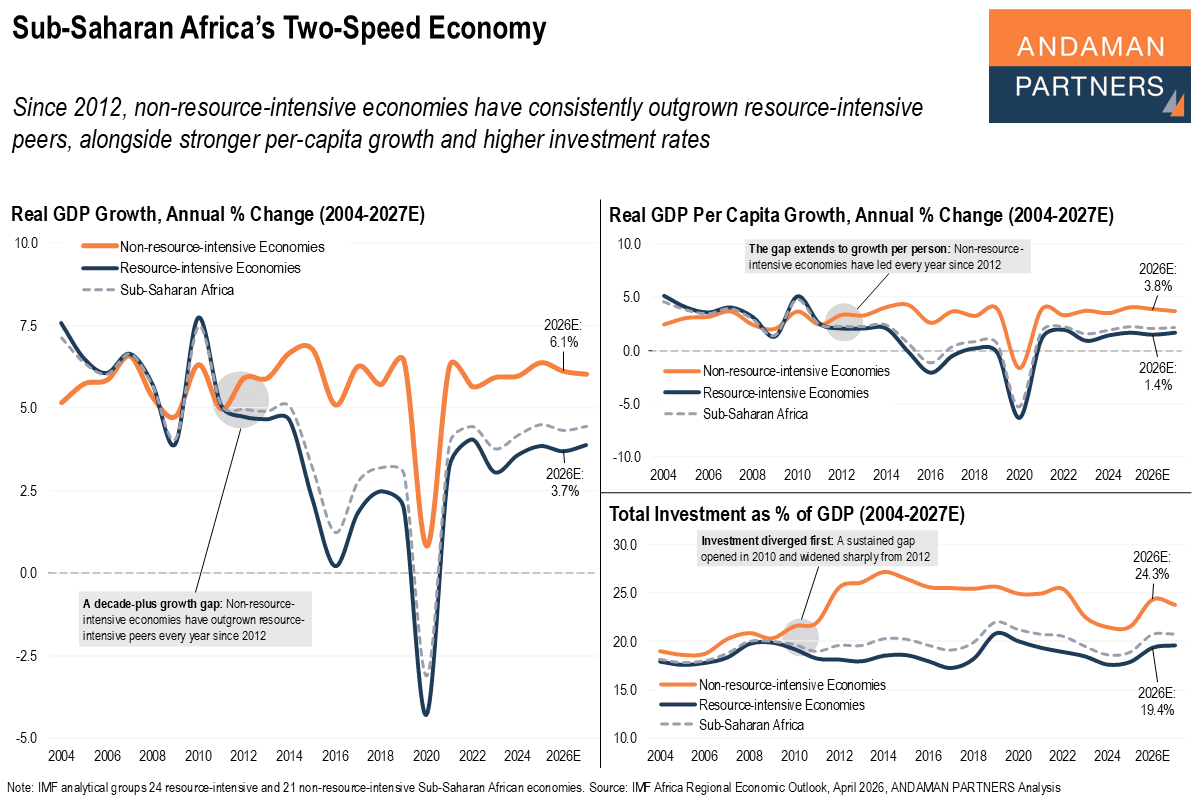
Since 2012, non-resource-intensive economies have consistently outgrown resource-intensive peers
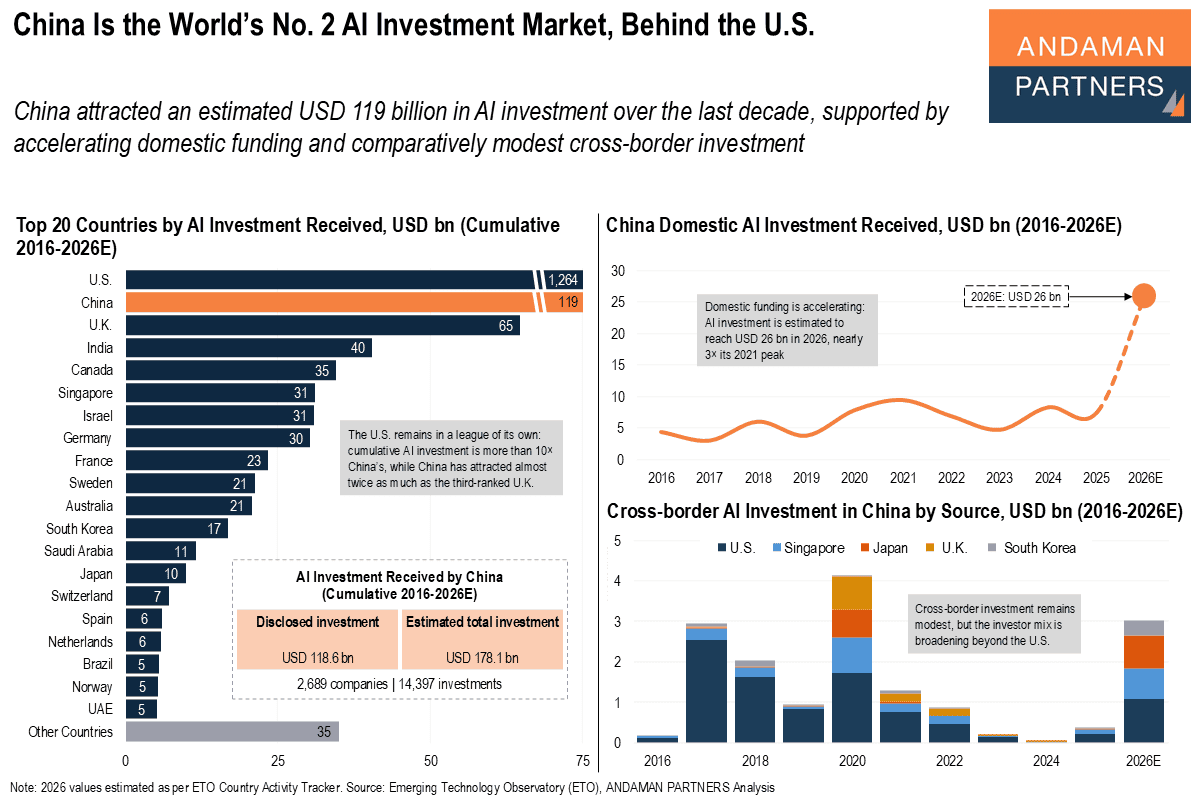
China attracted USD 119 billion in AI investment over the last decade, supported by accelerating domestic funding.
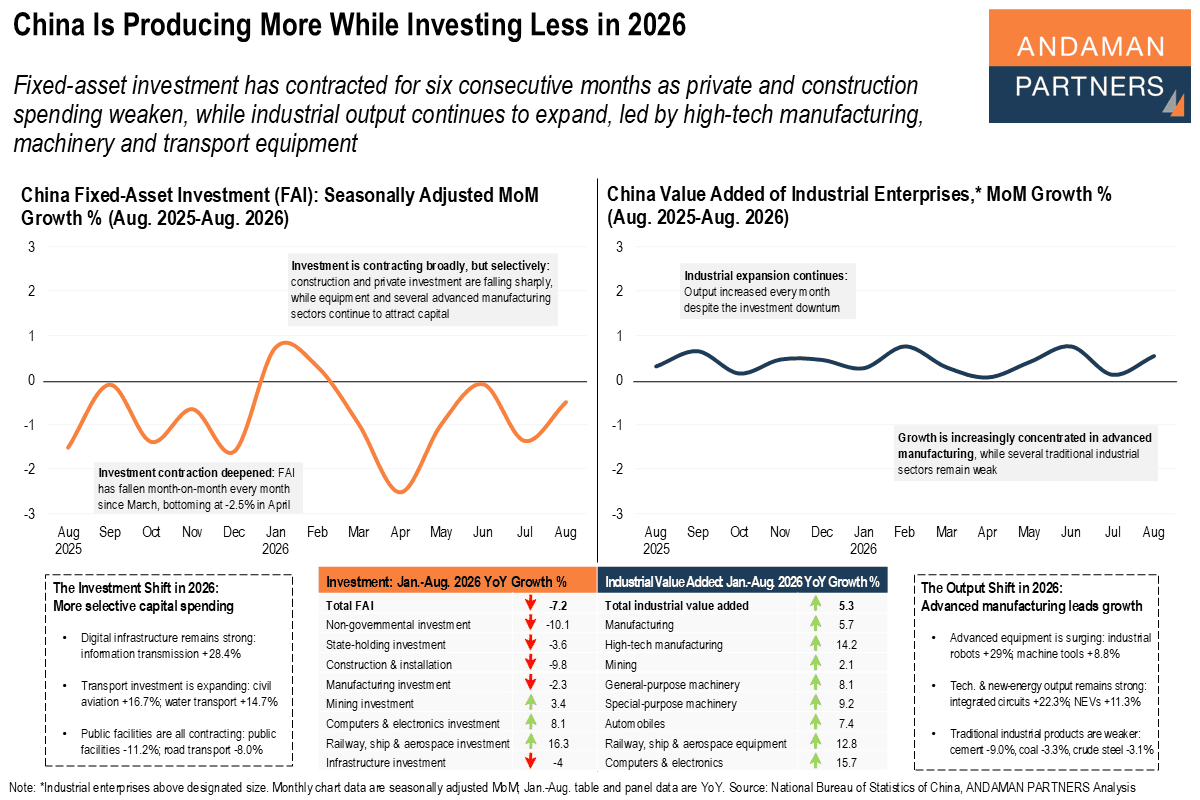
FAI has contracted for six consecutive months as private and construction spending weakens, while industrial output continues to expand.
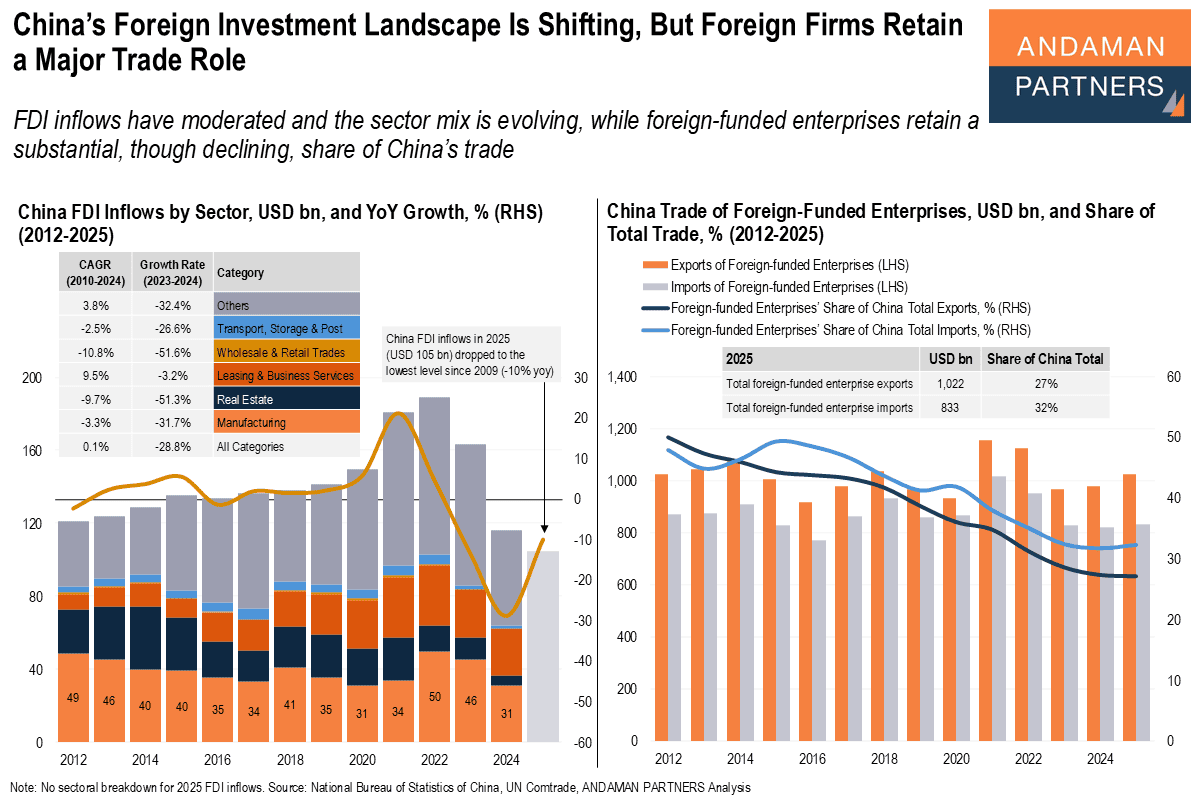
FDI inflows have moderated and the sector mix is evolving, while foreign-funded enterprises retain a substantial, though declining, share of China’s trade.
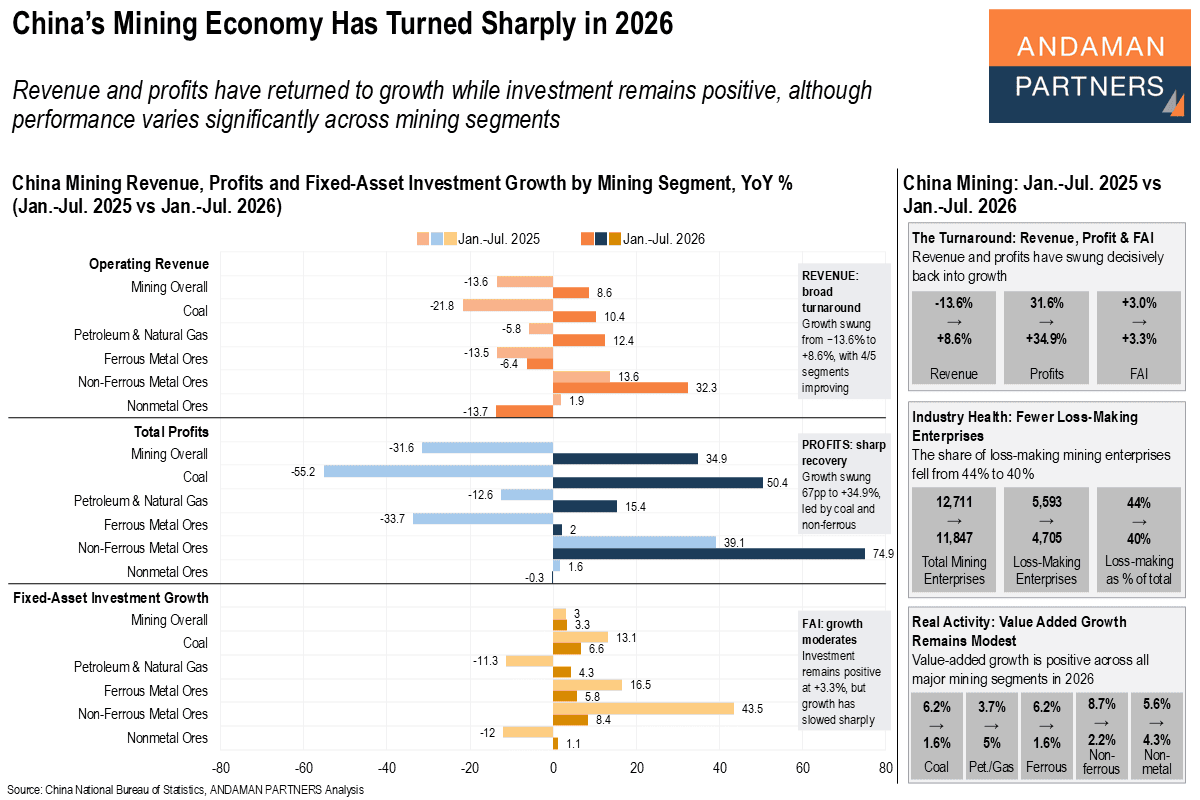
Revenue and profits have returned to growth while investment remains positive, although performance varies significantly across segments
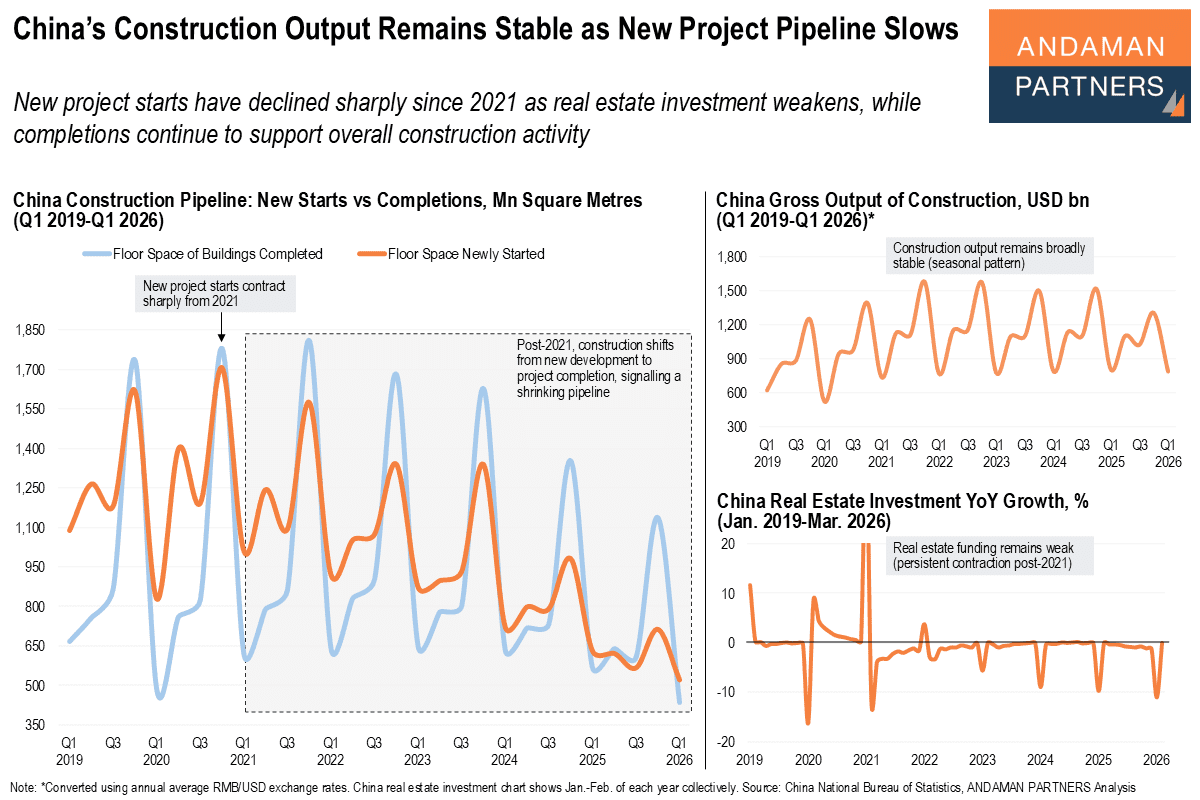
New project starts have declined sharply since 2021 as real estate investment weakens, while completions continue to support overall construction activity.
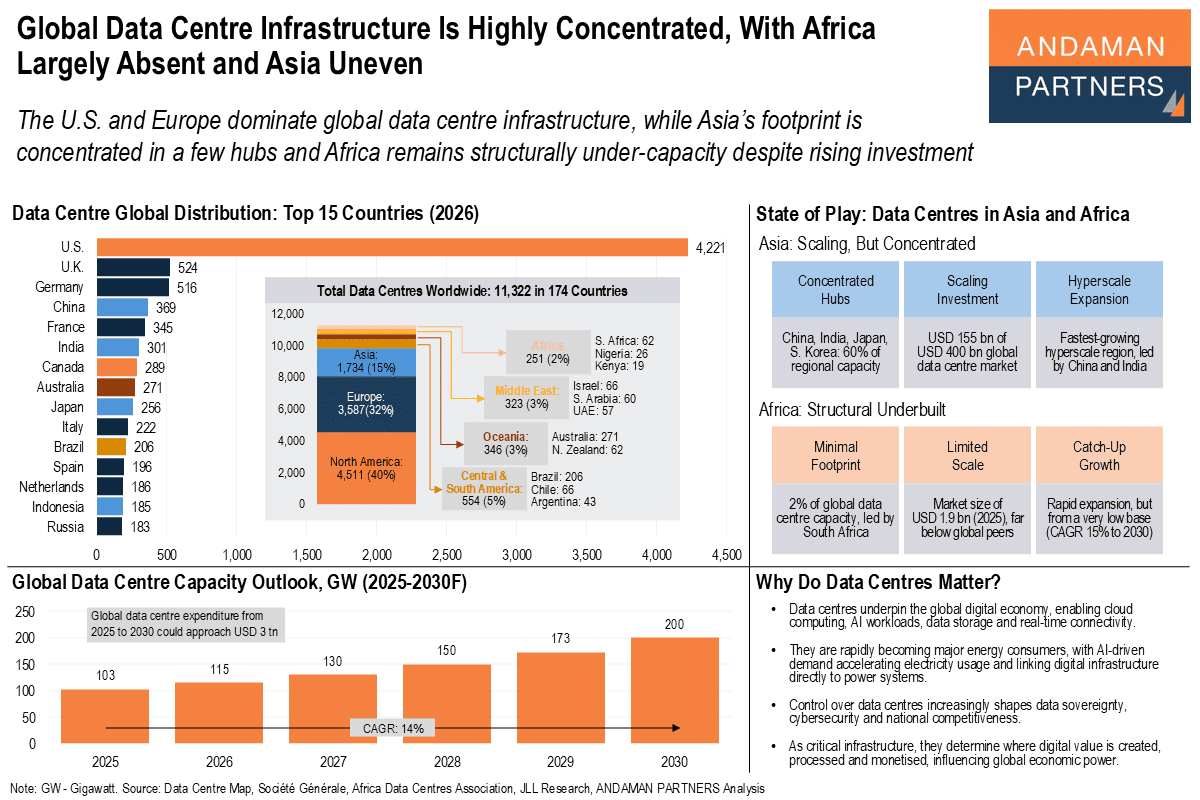
The U.S. and Europe dominate global data centre infrastructure, while Asia’s footprint is concentrated in a few hubs
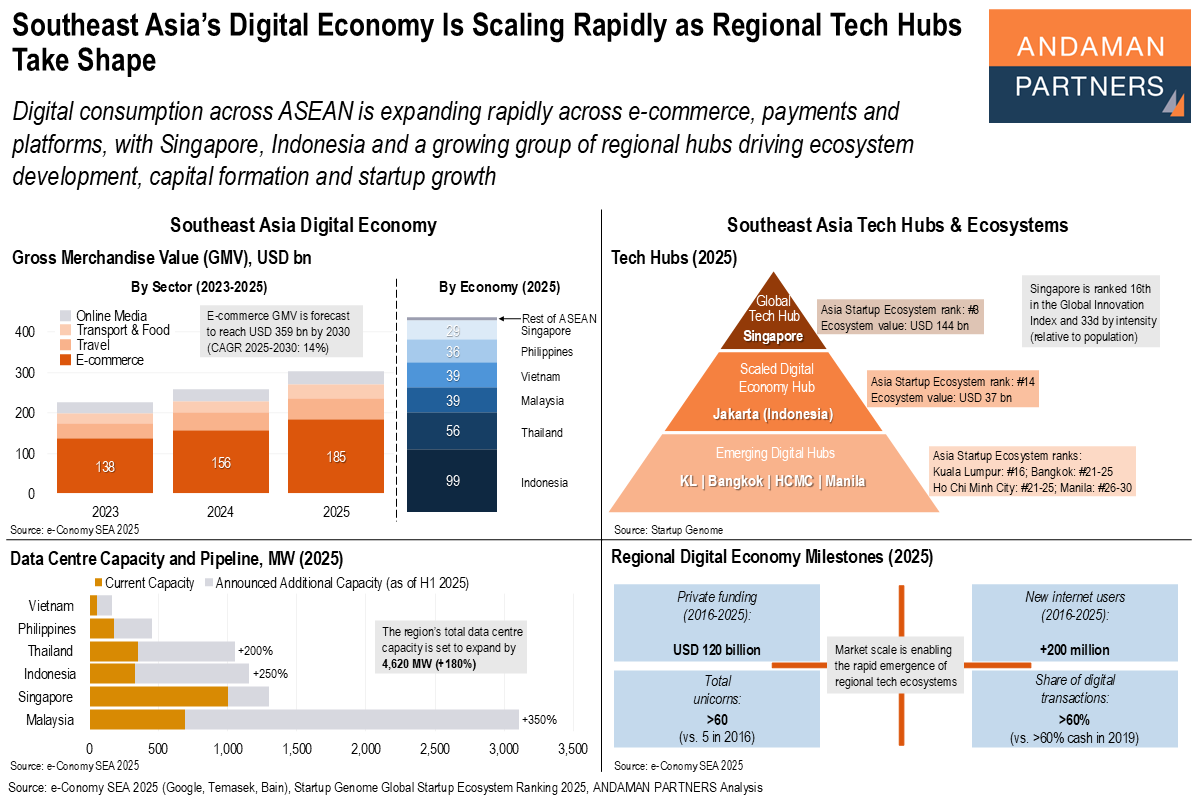
Digital consumption across Southeast Asia is expanding rapidly across e-commerce, payments and platforms.
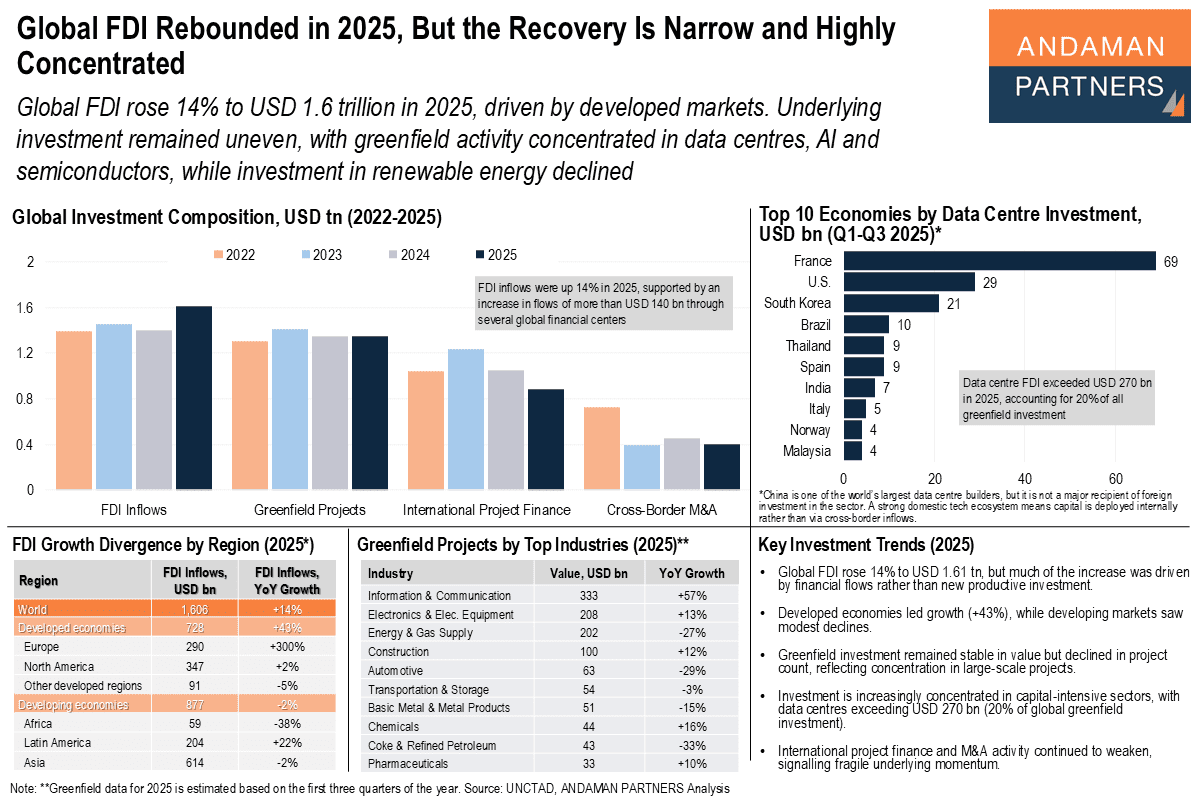
Investment remained uneven, with greenfield activity concentrated in data centres, AI and semiconductors.