U.S. Imports and the Shifting Architecture of Global Trade (1987-2025)
As the world’s leading importer, U.S. imports over nearly four decades have reflected the evolving patterns of global trade—from early globalisation and China’s rise to today’s supply-chain rewiring through China+1 and nearshoring.
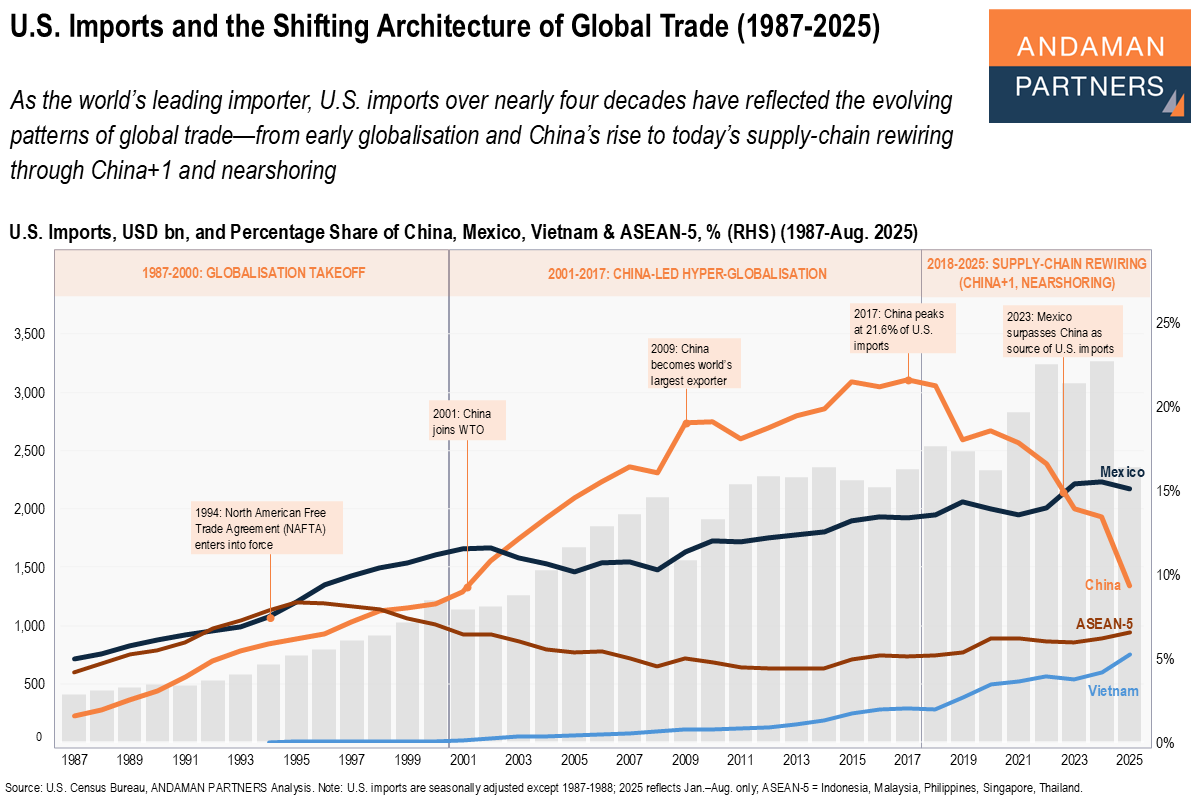
Over nearly four decades, U.S. imports have provided the most unambiguous indication of significant shifts in the global trading system. From the late 1980s through 2000, the U.S. absorbed rising volumes of goods as globalisation took off, supply chains lengthened and manufacturers dispersed production across North America and Asia.
This period was the foundational era of modern trade integration, defined by tariff liberalisation, the commencement of the North American Free Trade Agreement (NAFTA) in 1994 and the early stages of offshore manufacturing in Mexico and the Association of Southeast Asian Nations (ASEAN) economies.
From 2001 to 2017, globalisation entered its China-led phase. China’s WTO accession triggered the fastest and most extensive supply-chain integration in modern economic history. China became the world’s largest exporter in 2009 and reached a peak share of 21.6% of all U.S. imports in 2017, reflecting its central role in global electronics, machinery, consumer goods and intermediate components.
U.S. import patterns during this period capture the consolidation of China-centric supply chains and the deep interdependence that characterised the hyper-globalisation era.
Since 2018, the structure of U.S. imports has shifted sharply as global trade entered a new phase of diversification and resilience. China’s share of U.S. imports has fallen rapidly. At the same time, Mexico has risen to become the U.S.’s largest import source, and Vietnam and the ASEAN-5 economies (Indonesia, Malaysia, the Philippines, Singapore and Thailand) have steadily gained ground as China+1 sourcing options.
This supply-chain rewiring period reflects a long-term, organic rebalancing of global production, driven by geopolitics, cost dynamics, industrial policy and corporate strategies to build multi-node, regionally anchored supply networks. The result is a more distributed global trade architecture, with China still central but no longer singular.
Also by ANDAMAN PARTNERS:
ANDAMAN PARTNERS supports international business ventures and growth. We help launch global initiatives and accelerate successful expansion across borders. If your business, operations or project requires cross-border support, contact connect@andamanpartners.com.

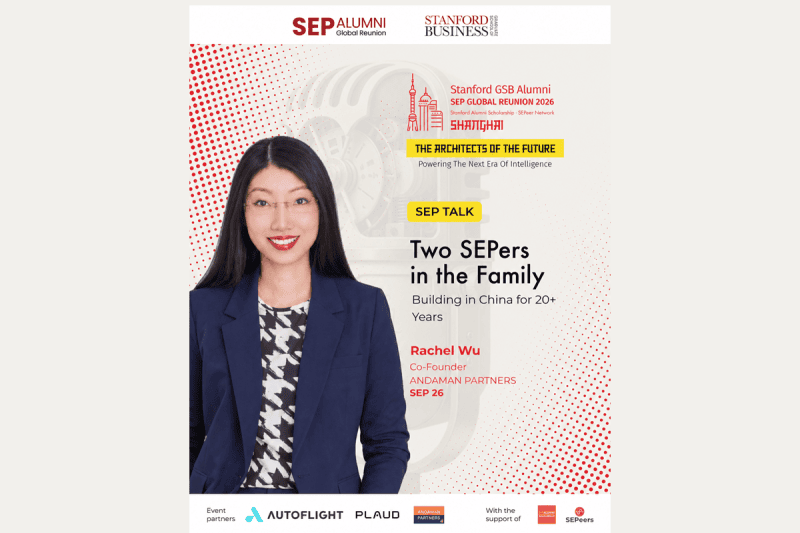
ANDAMAN PARTNERS Co-Founder Rachel Wu to Deliver Talk at SEP Global Reunion 2026 in Shanghai, China
Rachel will deliver a talk at the event entitled ‘Two SEPers in the Family – Building in China for 20+ Years’
ANDAMAN PARTNERS to Attend Stanford Executive Programme Global Reunion 2026 in Shanghai, China
ANDAMAN PARTNERS will attend the SEP Global Reunion 2026 in Shanghai, China, from 28 October to 1 November 2026
ANDAMAN PARTNERS to Attend 2026 IMF & World Bank Annual Meetings in Bangkok, Thailand
ANDAMAN PARTNERS will attend the IMF & World Bank Annual Meetings in Bangkok on 12-18 October 2026
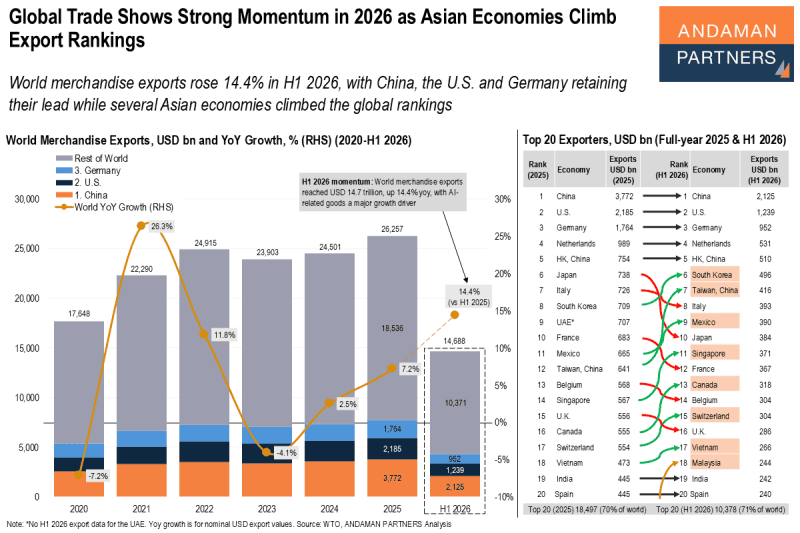
Global Trade Shows Strong Momentum in 2026 as Asian Economies Climb Export Rankings
World merchandise exports rose 14.4% in H1 2026, with several Asian economies climbing the global rankings
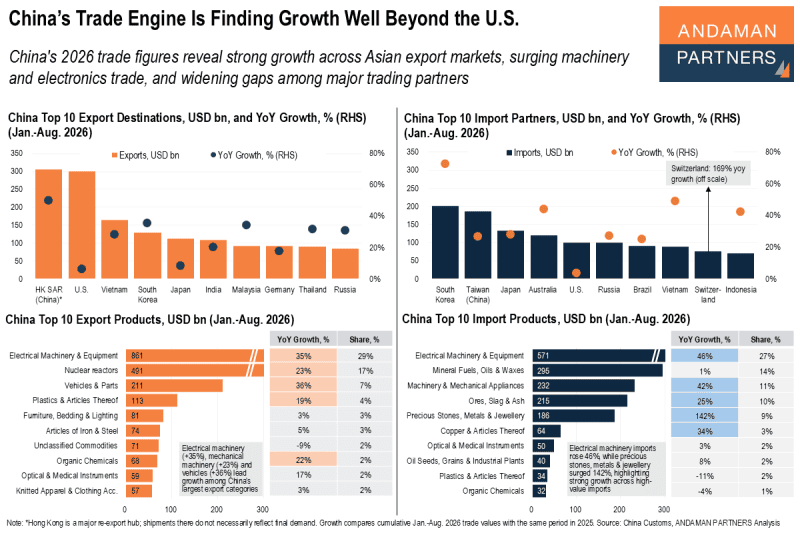
China’s Trade Engine Is Finding Growth Well Beyond the U.S.
China’s 2026 trade figures reveal strong growth across Asian export markets and surging machinery and electronics trade
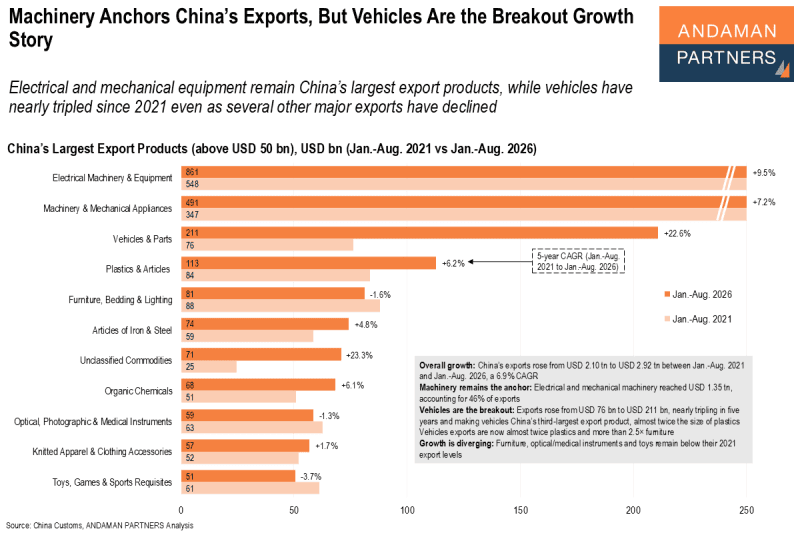
Machinery Anchors China’s Exports, But Vehicles Are the Breakout Growth Story
Electrical and mechanical equipment remain China’s largest export products, while vehicles have nearly tripled since 2021