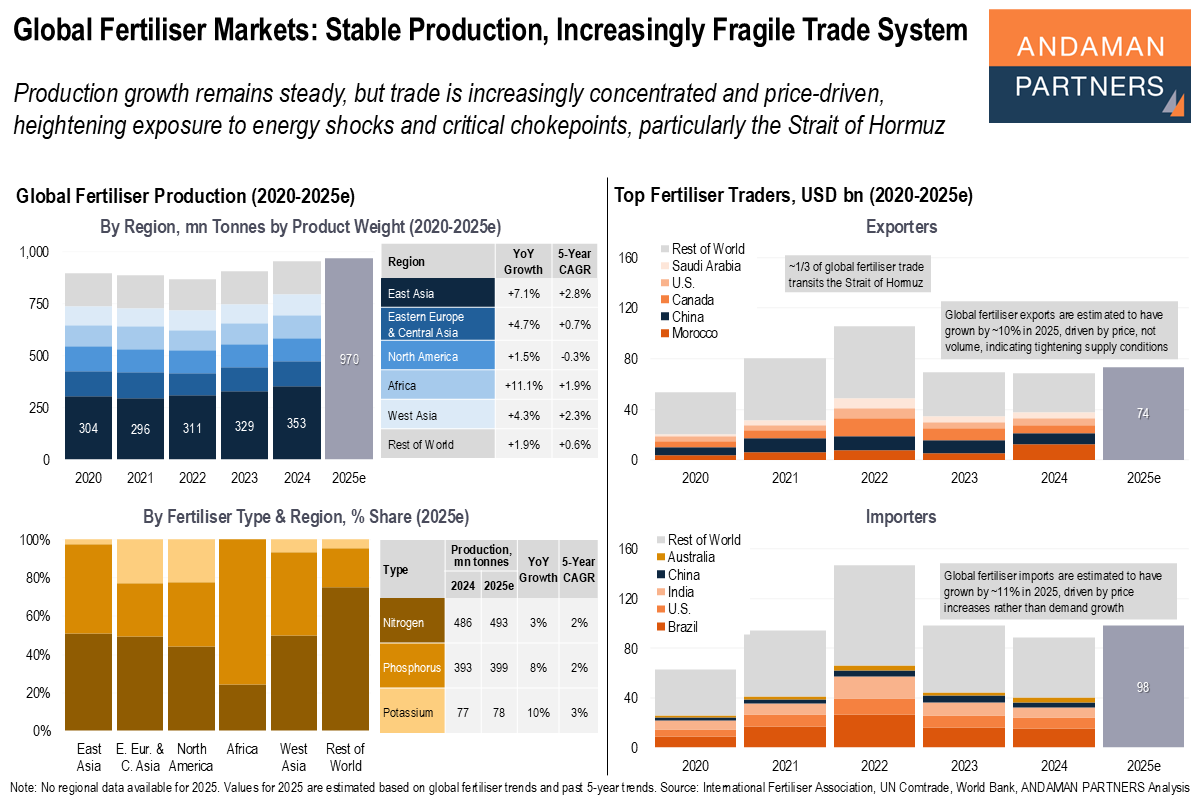
Production growth remains steady, but trade is increasingly concentrated and price-driven, heightening exposure to energy shocks and critical chokepoints, particularly the Strait of Hormuz.
Global fertiliser markets in 2025 present a deceptively stable picture on the supply side, but a far more fragile reality in trade. Production continues to expand gradually, reaching an estimated 970 million tonnes (product weight), with growth broadly distributed across Asia, Africa and other emerging regions.
However, this growth remains constrained by the energy-intensive nature of fertiliser production, particularly nitrogen, which is closely tied to natural gas, limiting the system’s ability to respond quickly to shocks. At the same time, the nutrient mix highlights structurally different risk profiles: nitrogen markets are energy-dependent, while phosphates and potash are more geographically concentrated in a handful of producers such as Morocco, Canada and Russia.
The more significant shift is visible in trade. Global fertiliser trade values are rising in 2025, but this reflects price increases rather than meaningful volume expansion, indicating tightening supply conditions. This dynamic is increasingly shaped by geopolitical exposure, most notably in the Middle East. An estimated 30-33% of the global fertiliser trade, particularly nitrogen-based products such as urea and ammonia, transits through the Strait of Hormuz, with roughly 45-50% of global urea exports originating from Middle Eastern producers. This creates a critical chokepoint in the global system.
For import-dependent markets such as India, Brazil and large parts of Africa, even partial disruptions to Hormuz-linked routes can lead to immediate price spikes, higher freight costs and supply delays. While rerouting and existing inventories can prevent a full supply collapse, the system operates with relatively low buffers, amplifying volatility.
Importantly, energy markets reinforce this fragility: any disruption affecting Gulf gas exports simultaneously raises production costs for nitrogen fertilisers. The result is a market that appears balanced at the production level but is increasingly exposed to short-term shocks, price volatility and geopolitical risk through its trade architecture.
Also by ANDAMAN PARTNERS:
ANDAMAN PARTNERS supports international business ventures and growth. We help launch global initiatives and accelerate successful expansion across borders. If your business, operations or project requires cross-border support, contact connect@andamanpartners.com.
Global Fertiliser Markets

ANDAMAN PARTNERS to Attend China Mining 2026 in Tianjin, China
ANDAMAN PARTNERS will attend the China Mining Conference and Exhibition in Tianjin, China, on 10-12 September 2026
ANDAMAN PARTNERS at the Singapore Institute of Directors Annual Conference 2026
ANDAMAN PARTNERS at the Singapore Institute of Directors Conference 2026 in Singapore on 28 August 2026
ANDAMAN PARTNERS Attended the Australia Governance Summit 2026 in Sydney
ANDAMAN PARTNERS Co-Founder Kobus van der Wath attended the Australia Governance Summit (AGS26) in Sydney, Australia.
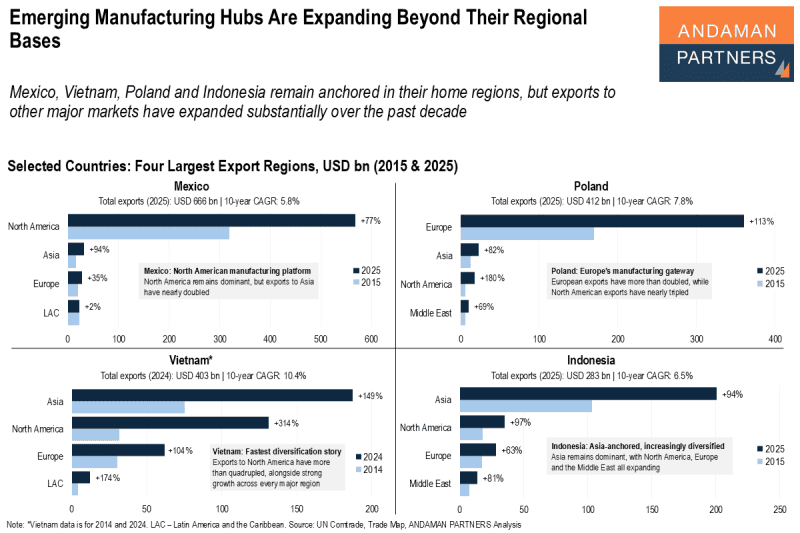
Emerging Manufacturing Hubs Are Expanding Beyond Their Regional Bases
Mexico, Vietnam, Poland and Indonesia remain anchored in their home regions, but exports to other major markets have expanded substantially
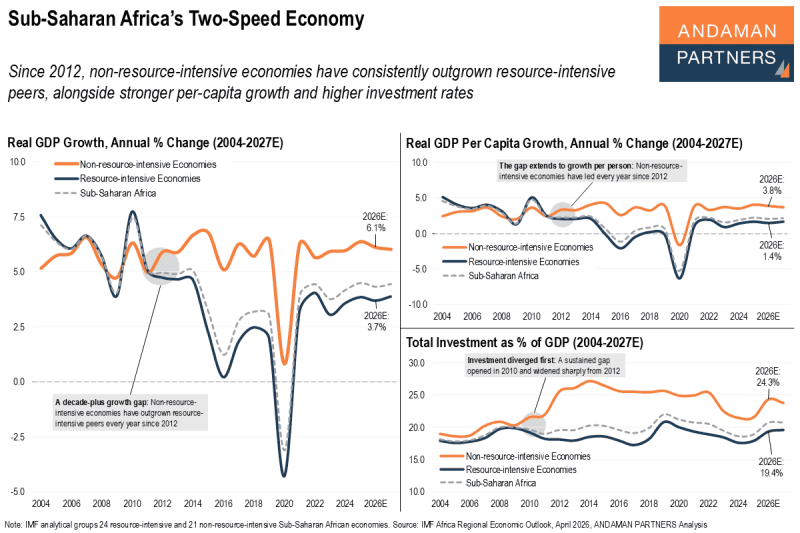
Sub-Saharan Africa’s Two-Speed Economy
Since 2012, non-resource-intensive economies have consistently outgrown resource-intensive peers
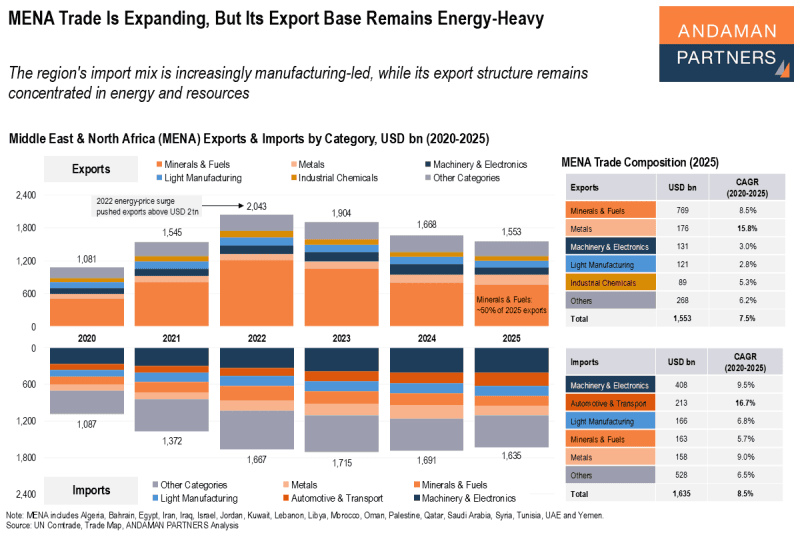
MENA Trade Is Expanding, But Its Export Base Remains Energy-Heavy
The region’s import mix is increasingly manufacturing-led, while its export structure remains concentrated in energy and resources.