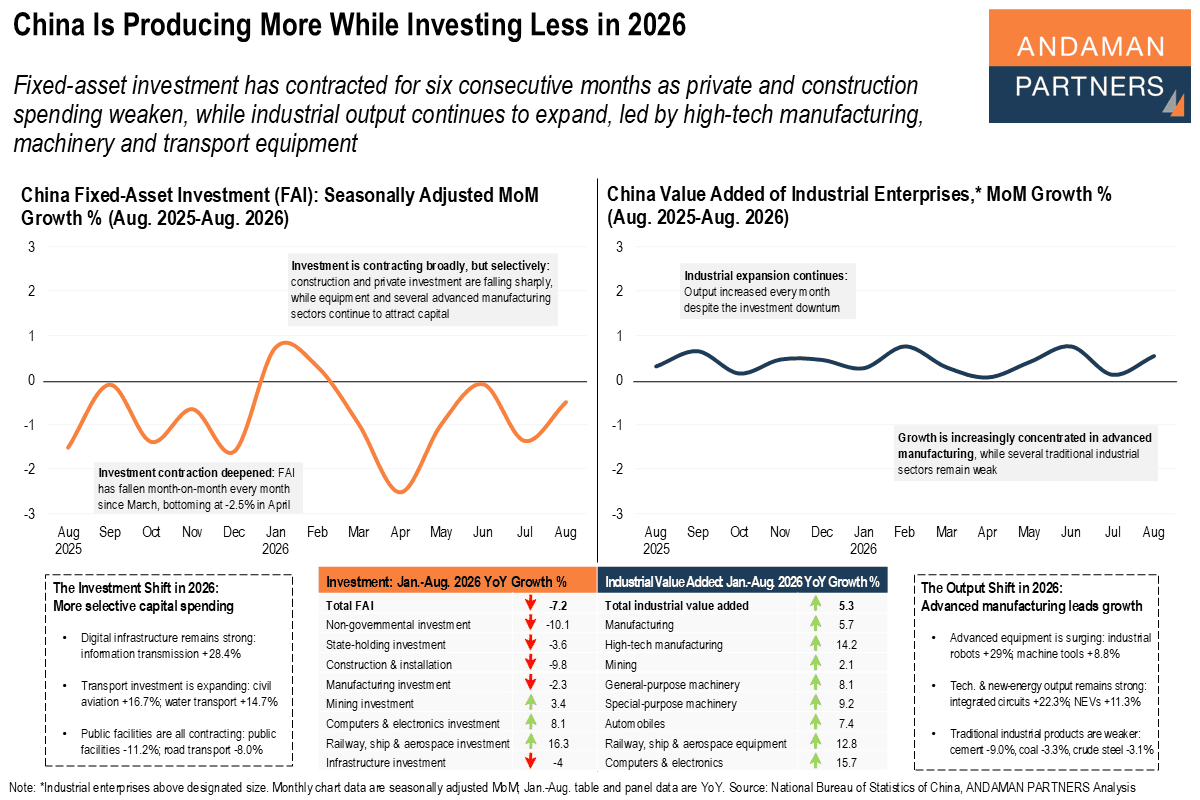
China Is Producing More While Investing Less in 2026
FAI has contracted for six consecutive months as private and construction spending weakens, while industrial output continues to expand.
FAI has contracted for six consecutive months as private and construction spending weakens, while industrial output continues to expand.
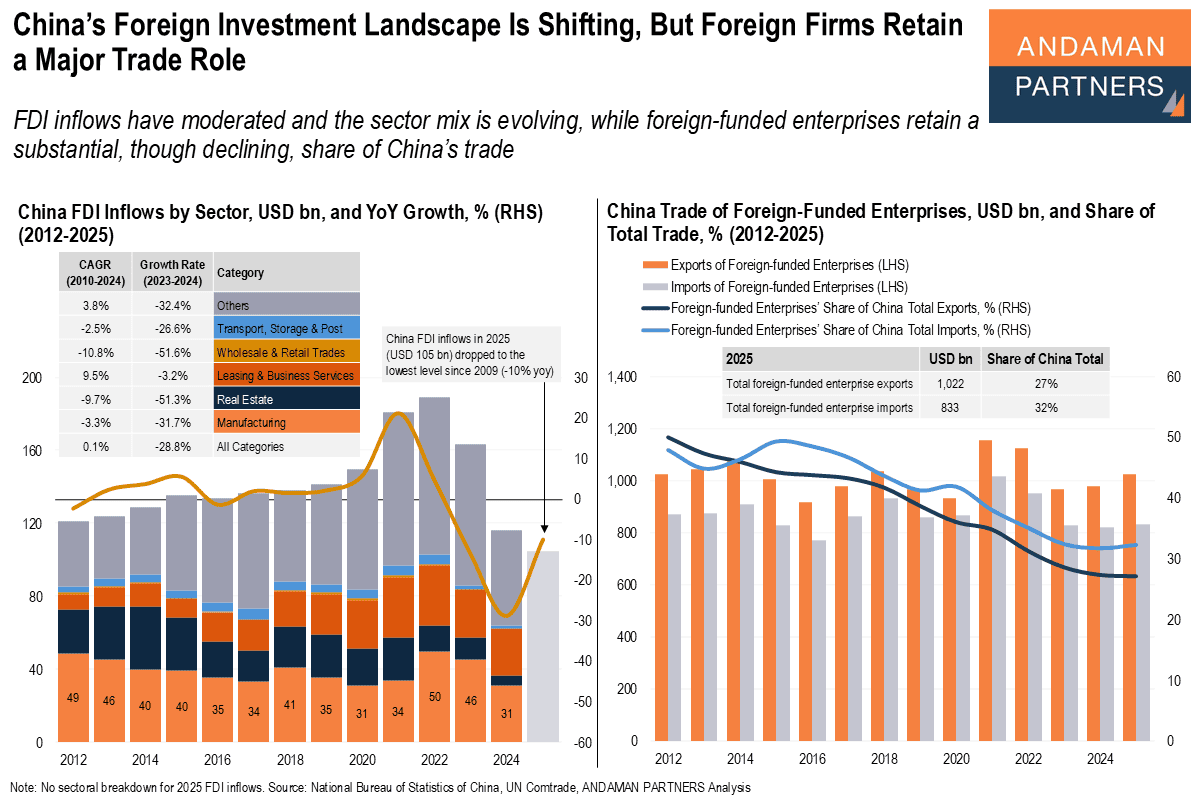
FDI inflows have moderated and the sector mix is evolving, while foreign-funded enterprises retain a substantial, though declining, share of China’s trade.
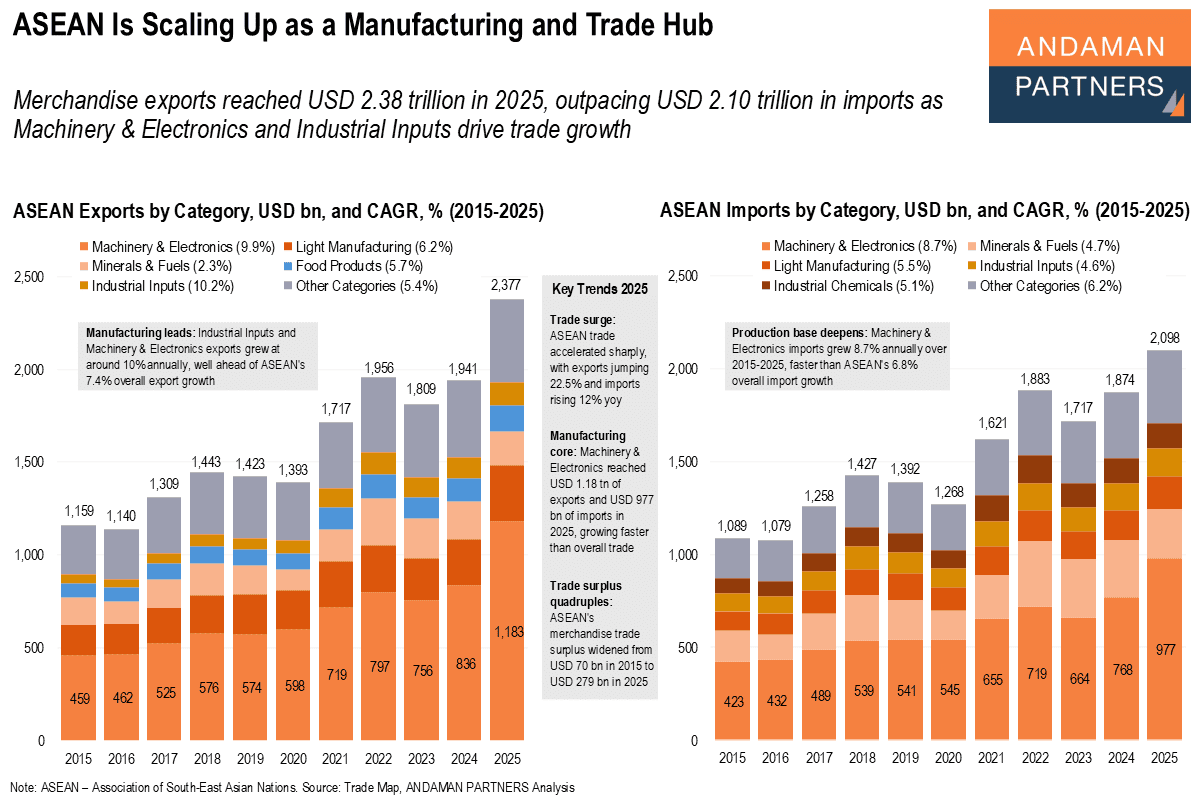
Merchandise exports reached USD 2.38 trillion in 2025, outpacing USD 2.10 trillion in imports
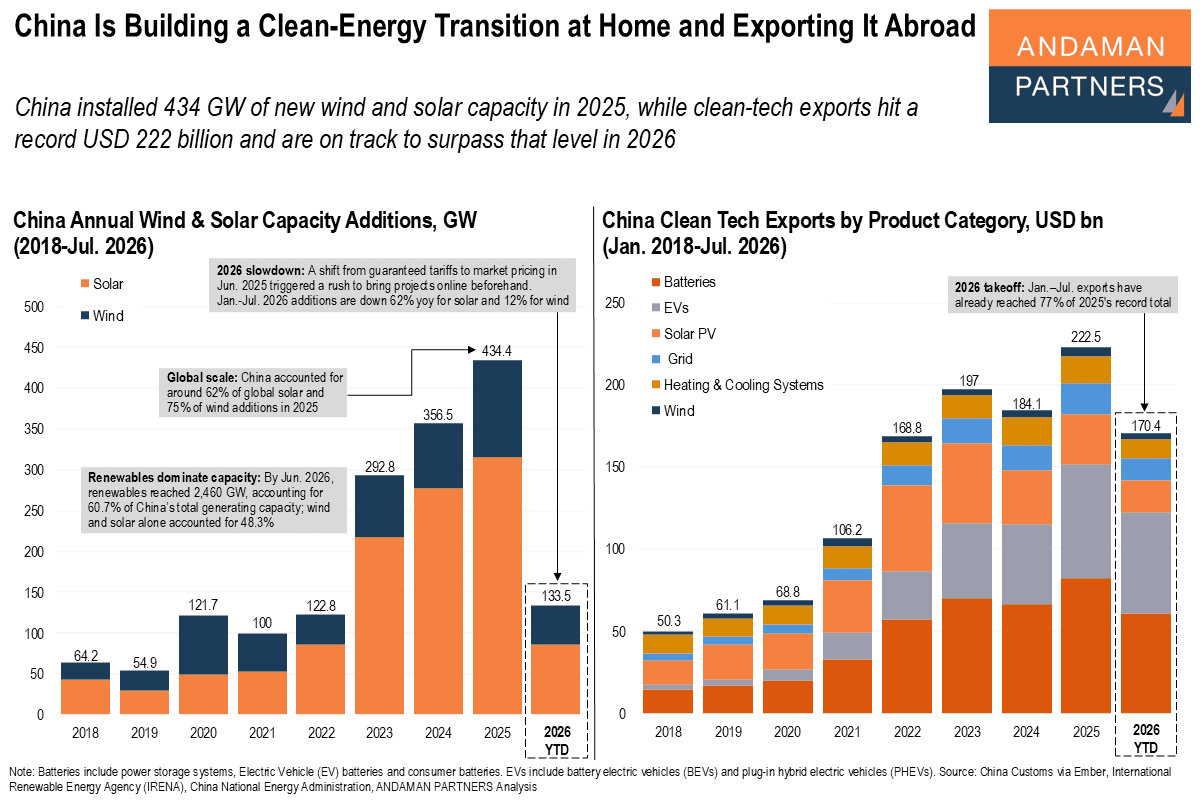
China installed 434 GW of new wind and solar capacity in 2025, while clean-tech exports hit a record level in 2026
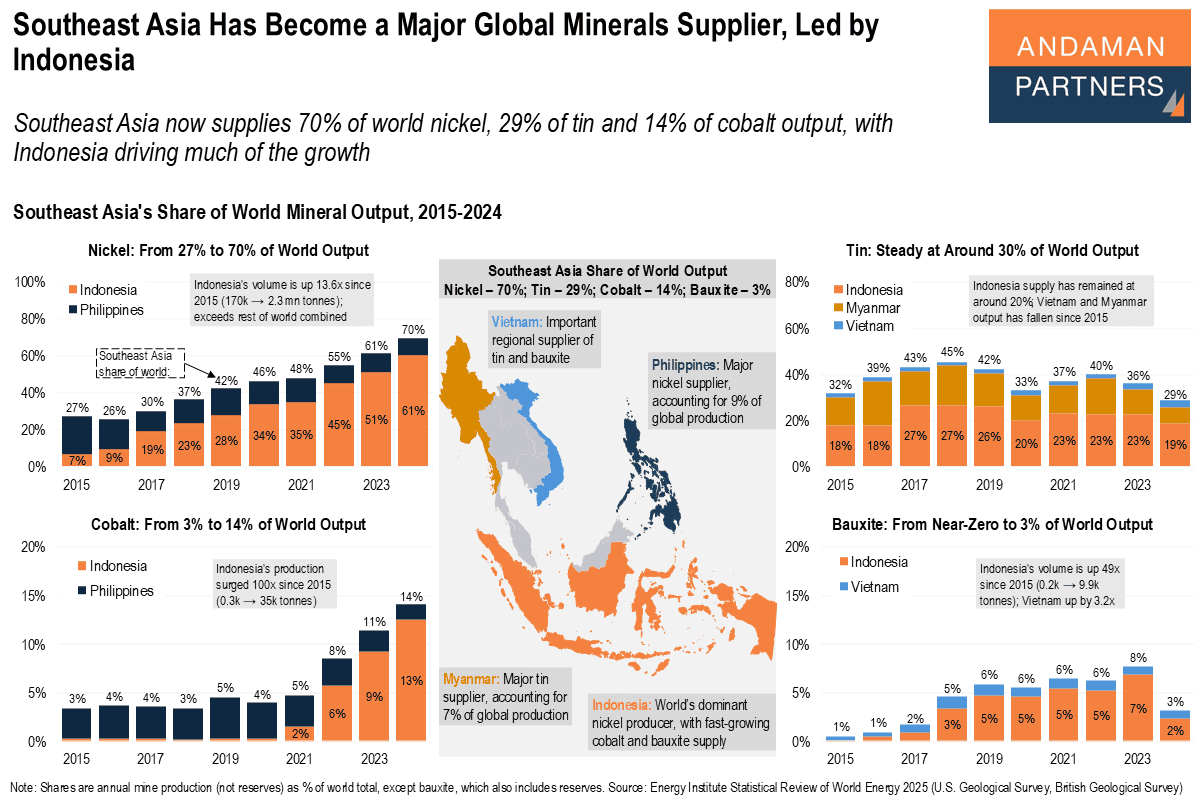
Southeast Asia now supplies 70% of world nickel, 29% of tin and 14% of cobalt output, with Indonesia driving much of the growth
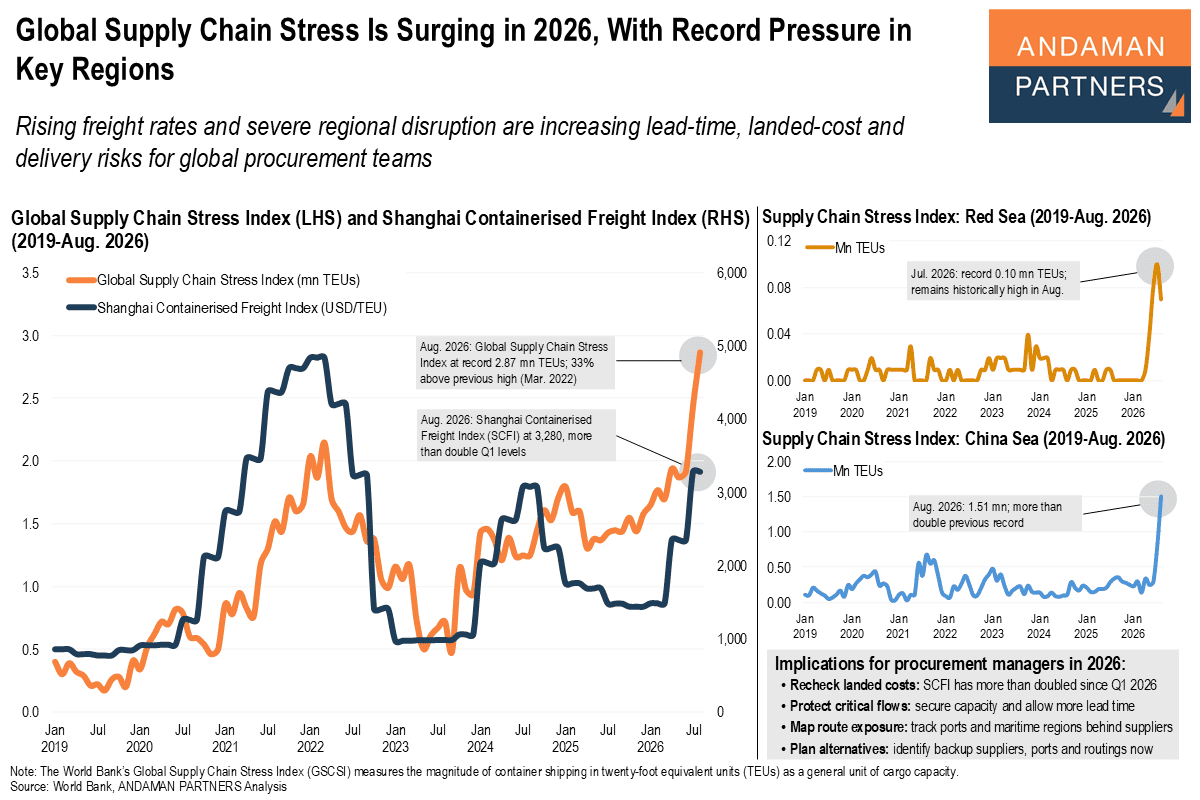
Rising freight rates and severe regional disruption are increasing lead-time, landed-cost and delivery risks for global procurement teams
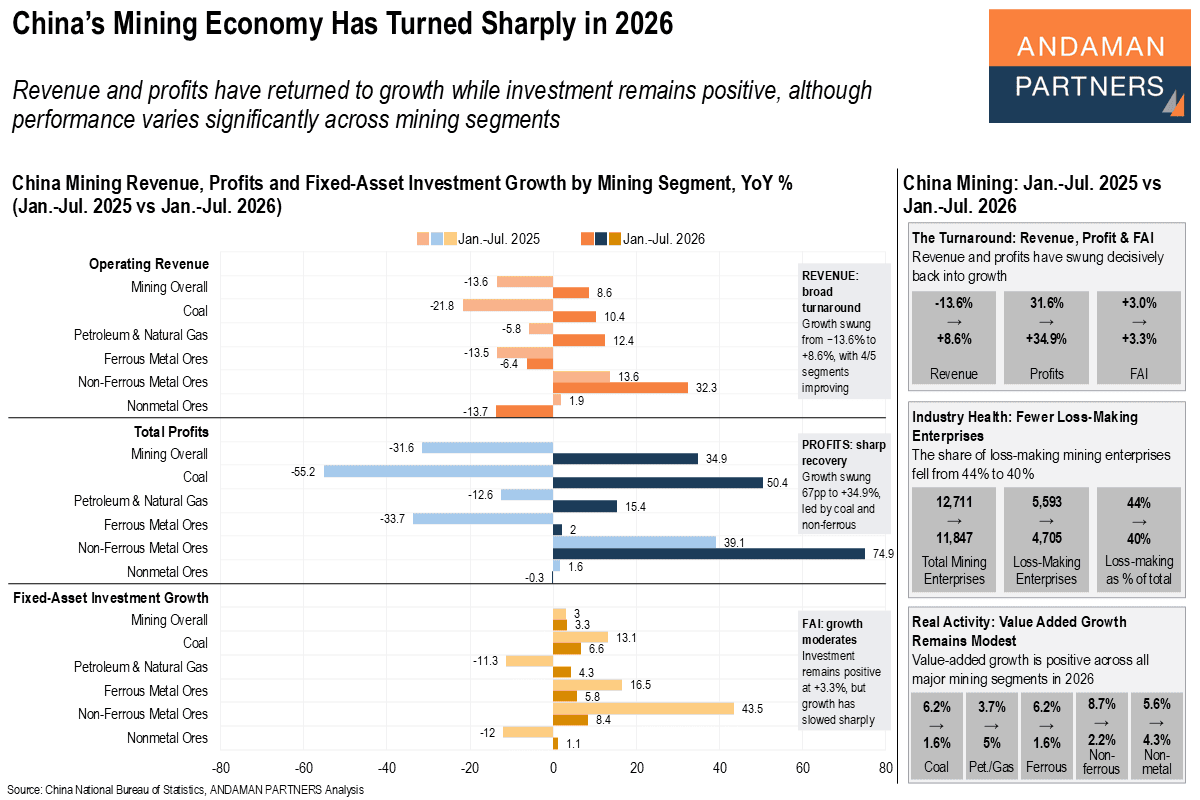
Revenue and profits have returned to growth while investment remains positive, although performance varies significantly across segments
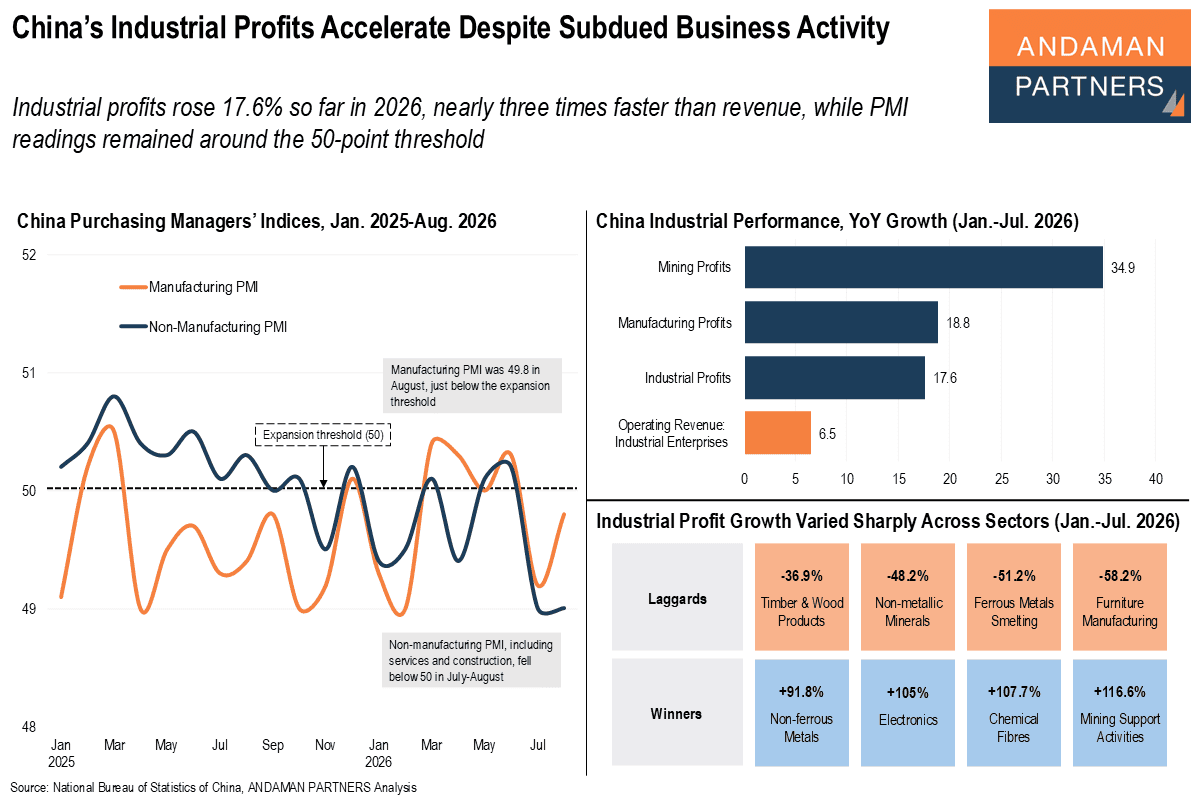
Industrial profits rose 17.6% so far in 2026, nearly three times faster than revenue, while PMI readings remained below 50
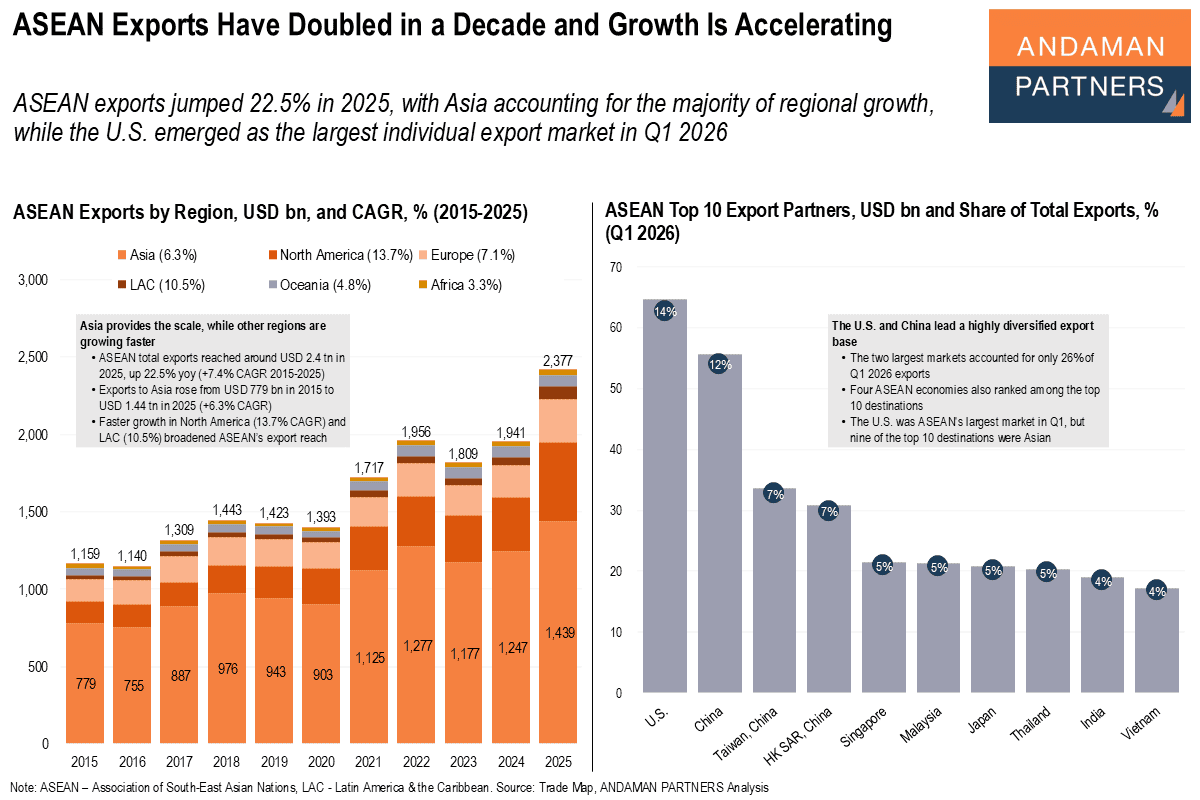
ASEAN exports jumped 22.5% in 2025, with Asia accounting for the majority of regional growth
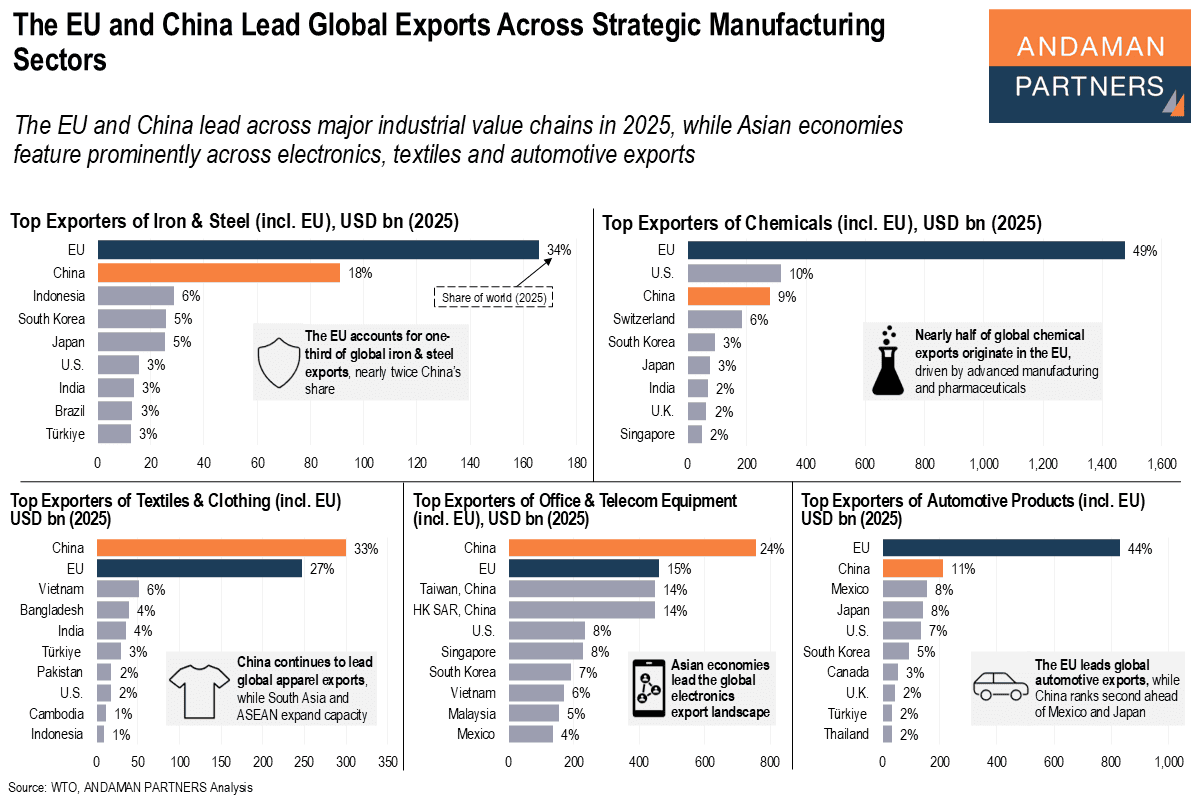
The EU and China lead across major industrial value chains in 2025, while Asian economies feature prominently in electronics, textiles and automotive