China Provincial Growth Map 2025
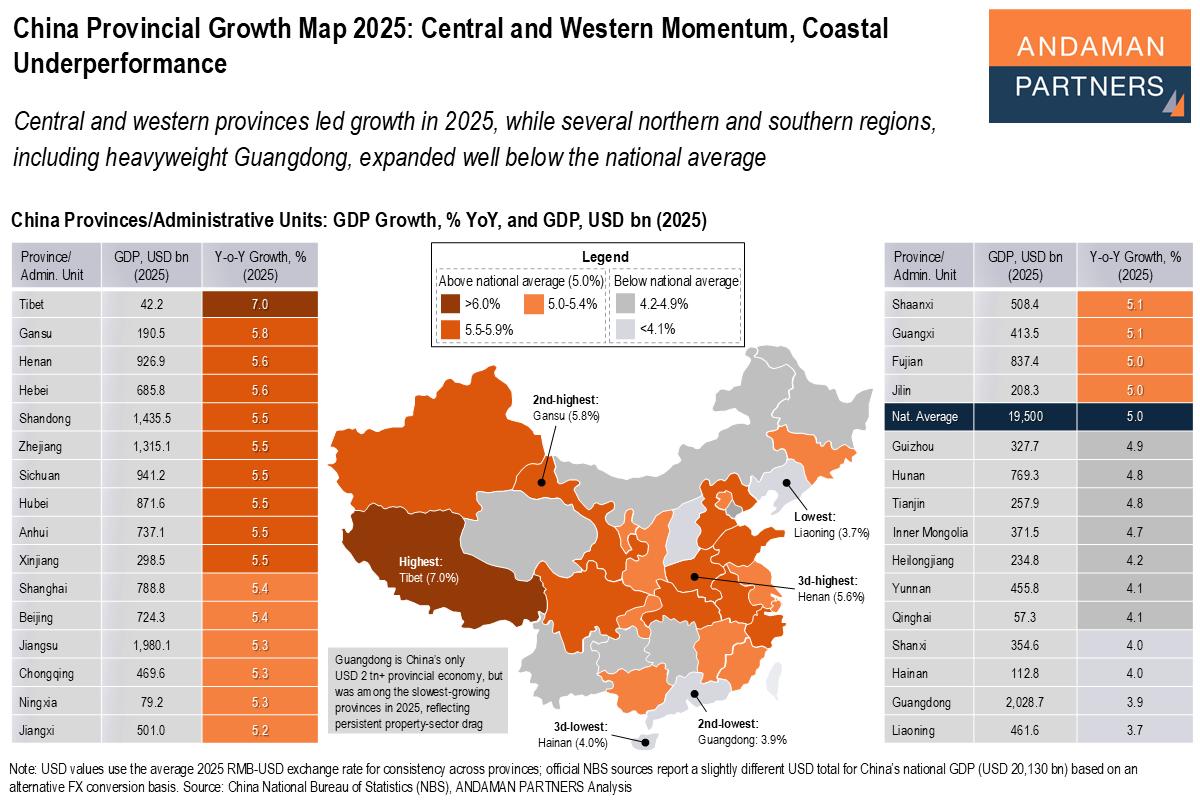
Central and western provinces led growth in 2025, while several northern and southern regions, including heavyweight Guangdong, expanded well below the national average.
China’s provincial growth map in 2025 highlights a clear regional divergence: momentum strengthened across the central and western interior, while several major coastal and peripheral provinces lagged the national pace.
On the upside, growth leadership came from the west and parts of central China. Tibet led all regions at 7.0%, followed by Gansu (5.8%) and Henan (5.6%), reinforcing that inland demand, public investment and infrastructure-heavy activity strongly supported growth in 2025.
A broad group of large central and eastern provinces also delivered solid above-average growth, including Hebei (5.6%), Shandong (5.5%), Zhejiang (5.5%), Sichuan (5.5%), Hubei (5.5%), Anhui (5.5%) and Xinjiang (5.5%). Major metropolises such as Shanghai (5.4%) and Beijing (5.4%) also outperformed modestly, while export-linked manufacturing giants like Jiangsu (5.3%) and Chongqing (5.3%) remained close to trend.
By contrast, underperformance was concentrated in parts of the northeast and the south. Liaoning posted the weakest growth at 3.7%, while Hainan (4.0%), Shanxi (4.0%), Qinghai (4.1%) and Yunnan (4.1%) all came in well below the national average of 5.0%.
The most notable laggard was Guangdong, China’s only USD 2 trillion-plus provincial economy, which expanded at just 3.9%. This reflects the continued drag from the property downturn, weaker construction-linked demand and slower momentum in consumer and export-facing activity. Guangdong’s slow pace highlights that even China’s most globally integrated coastal growth engines faced a more challenging operating environment in 2025.
Looking ahead to 2026, the key question is whether the inland-led pattern persists or whether coastal growth re-accelerates. If policy support continues to favour infrastructure investment, industrial upgrading and strategic manufacturing, central and western provinces are likely to remain resilient. However, a stabilisation in the property sector and a recovery in external demand would disproportionately benefit China’s coastal export and consumption hubs.
Overall, 2026 will likely be defined by whether China’s traditional coastal engines regain momentum or whether growth remains anchored in inland regions.
Also by ANDAMAN PARTNERS:
ANDAMAN PARTNERS supports international business ventures and growth. We help launch global initiatives and accelerate successful expansion across borders. If your business, operations or project requires cross-border support, contact connect@andamanpartners.com.

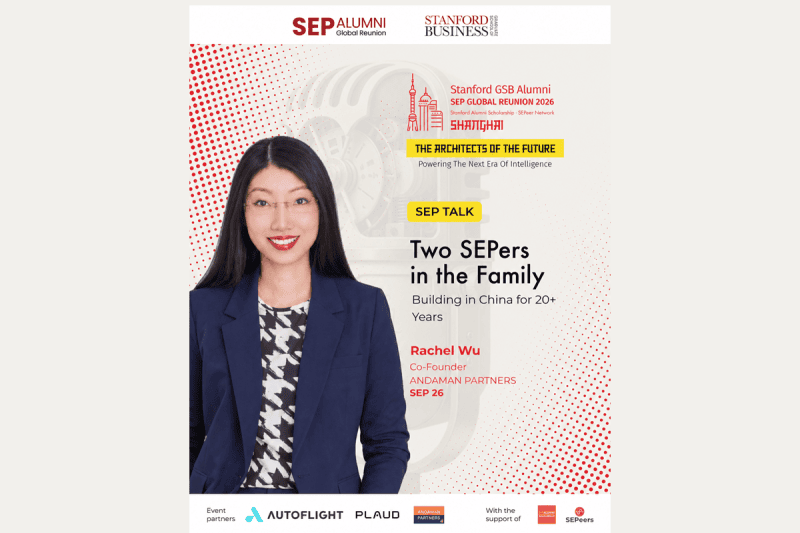
ANDAMAN PARTNERS Co-Founder Rachel Wu to Deliver Talk at SEP Global Reunion 2026 in Shanghai, China
Rachel will deliver a talk at the event entitled ‘Two SEPers in the Family – Building in China for 20+ Years’
ANDAMAN PARTNERS to Attend Stanford Executive Programme Global Reunion 2026 in Shanghai, China
ANDAMAN PARTNERS will attend the SEP Global Reunion 2026 in Shanghai, China, from 28 October to 1 November 2026
ANDAMAN PARTNERS to Attend 2026 IMF & World Bank Annual Meetings in Bangkok, Thailand
ANDAMAN PARTNERS will attend the IMF & World Bank Annual Meetings in Bangkok on 12-18 October 2026
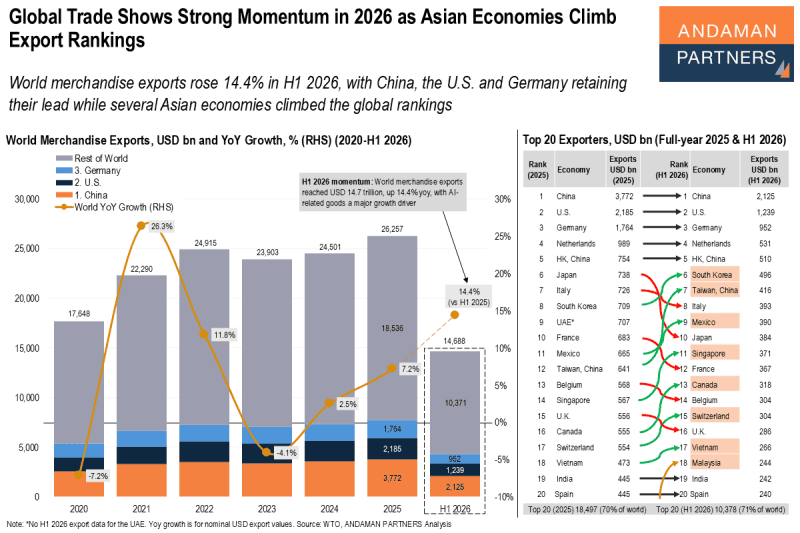
Global Trade Shows Strong Momentum in 2026 as Asian Economies Climb Export Rankings
World merchandise exports rose 14.4% in H1 2026, with several Asian economies climbing the global rankings
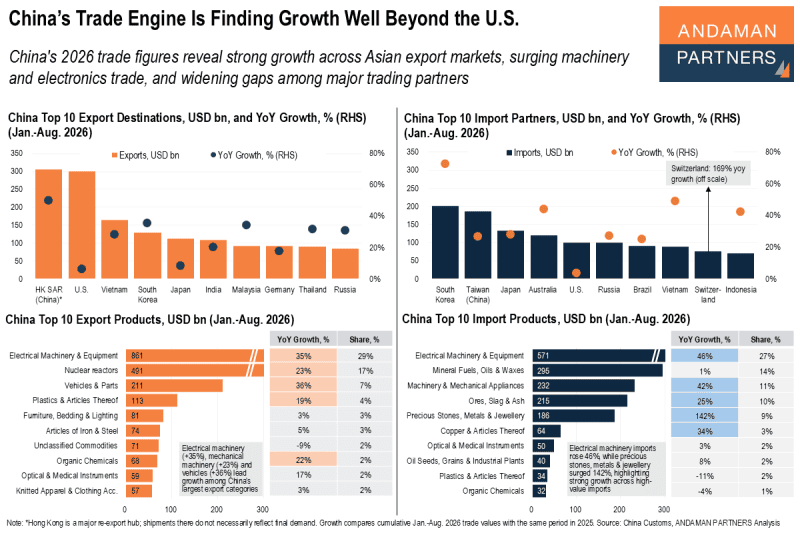
China’s Trade Engine Is Finding Growth Well Beyond the U.S.
China’s 2026 trade figures reveal strong growth across Asian export markets and surging machinery and electronics trade
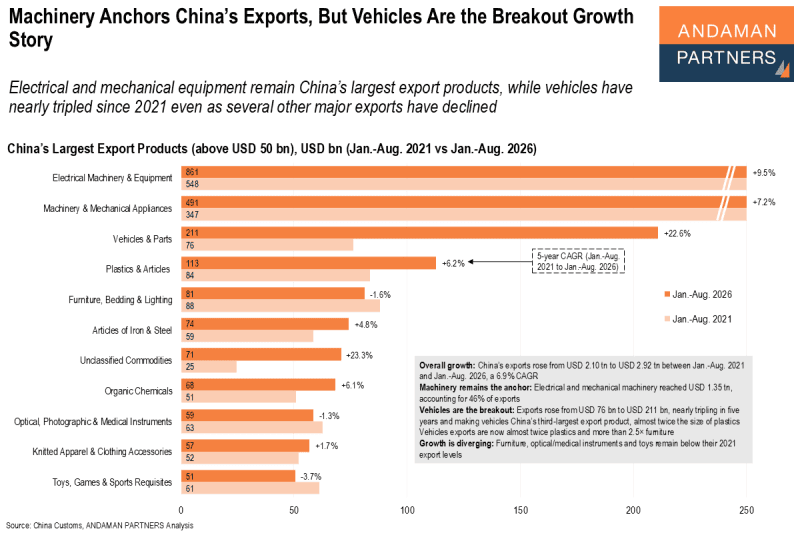
Machinery Anchors China’s Exports, But Vehicles Are the Breakout Growth Story
Electrical and mechanical equipment remain China’s largest export products, while vehicles have nearly tripled since 2021